



Fri, 9th Jan ’26
GAS
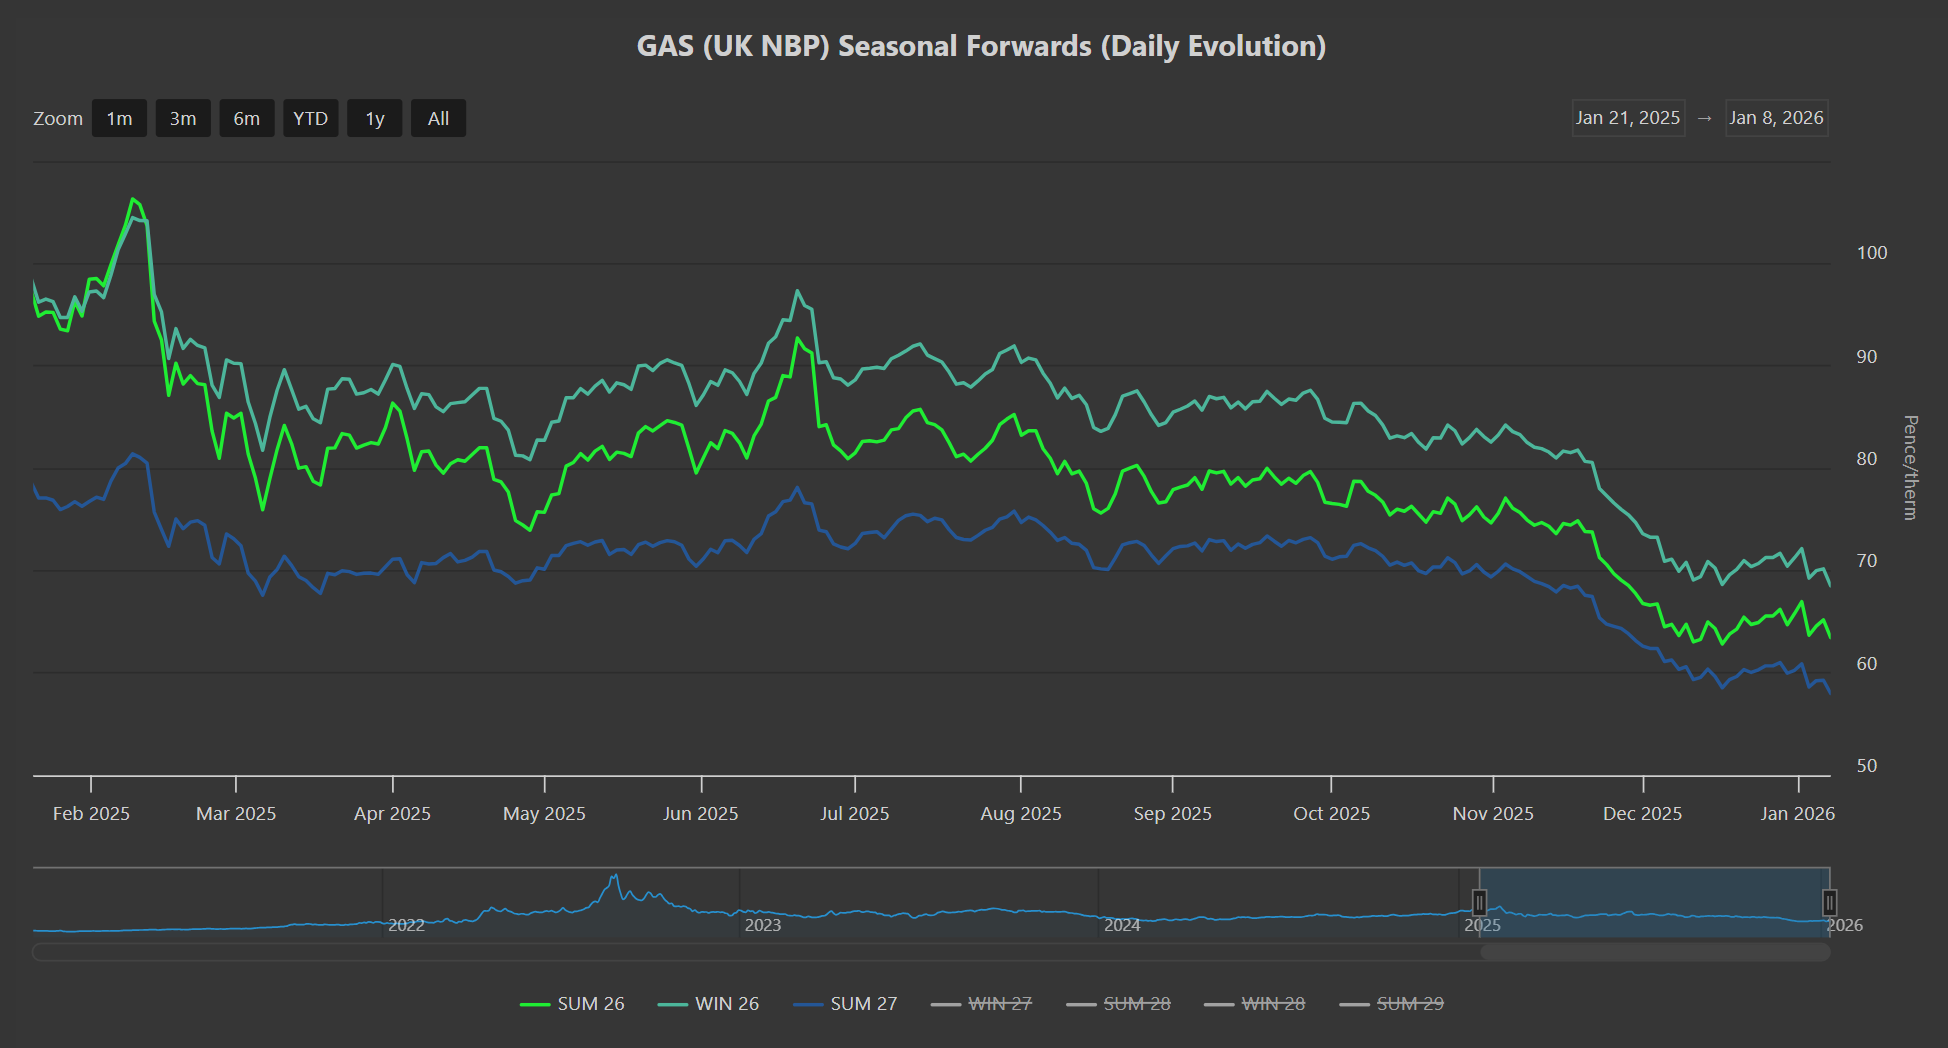
- Of the front 3-Seasons (Summer-26/Winter-26/Summer-27), Summer-26 delivery prices have enjoyed the steepest decline – prices for Summer-26 delivery are now at a 40% discount versus the highs last seen in Winter-24 (please see chart below).
- Prices opened lower again this morning despite the UK system being marginally short (demand outstripping supply forecast).
- It looks as though prices will close down on the week off the back of milder weather forecasts resulting in lower gas-for-power burn and, accordingly, reduced storage withdrawals.
- Beyond this weekend, temperatures above seasonal norms are expected to extend throughout northwest Europe.
- In other news, despite the EU’s recent announcements that purchase of Russian gas by EU states will be outlawed by the end of ’26, data just released confirms that 76.1% of Russia’s Yamal exports went to the EU!
- (Gas from the Yamal peninsula is exported via two separate methods: the Yamal–Europe pipeline (which goes to Poland and Germany) and the Yamal LNG project for shipping LNG.)
- All in all, a quiet week to start the year, but both near-and-far term delivery prices continue to soften despite the intermittently wintry conditions.
- Monthly Day-Ahead averages for January so far are holding steady at 76p/therm (or 2.6p/kwh exc. non-gas).
ELECTRICITY & CARBON
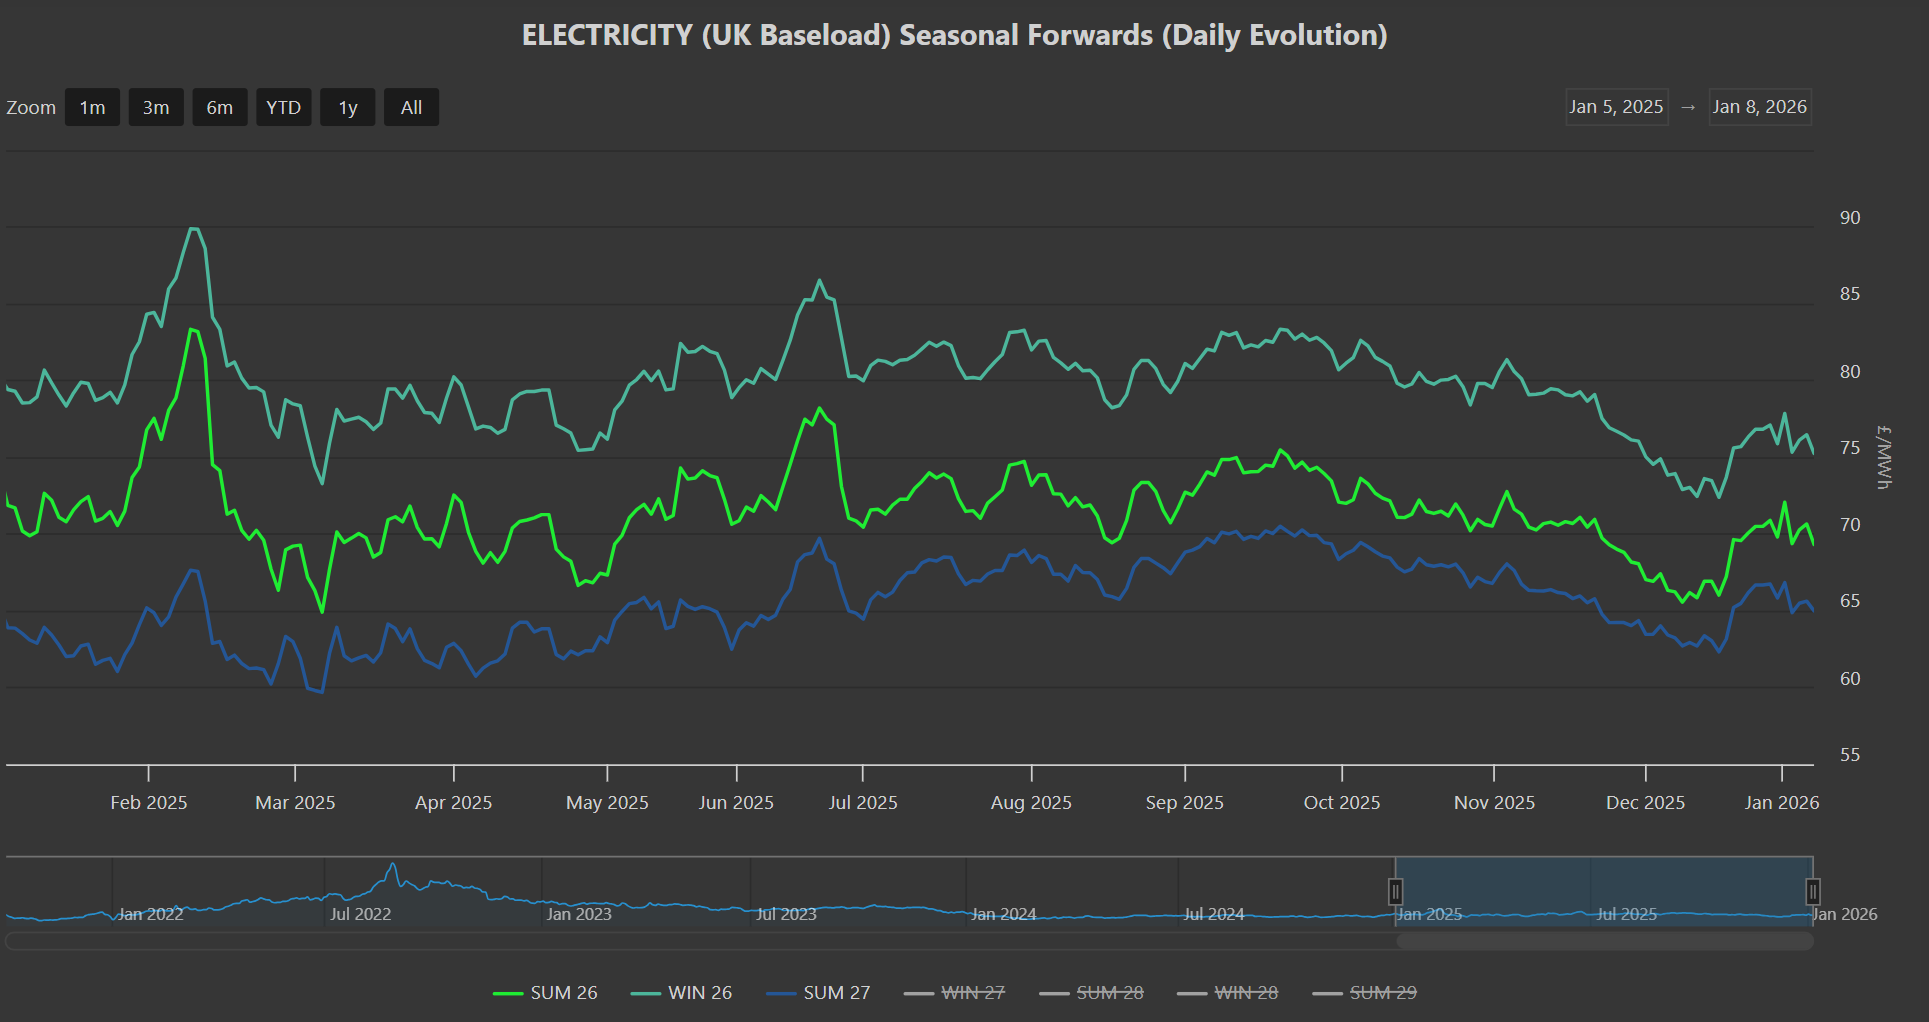
- Of the front 3-Seasons (Summer-26/Winter-26/Summer-27), both Summer-26 & Winter-26 delivery prices have enjoyed the steepest decline – both are now at a 17% discount versus the highs last seen in Winter-24 (please see chart below).
- Notably however, Summer-27 is barely altered versus its high last seen in Feb-25.
- This reflects significantly less volatility in electricity versus the much wider swings seen in global gas prices over the last 12 months – which in turn is no doubt a reflection that electricity generation is relying less and less on gas-for-power burn (and more on renewables).
- On the Carbon side of things, Dec-26 benchmark prices for UKAs are knocking on the door of £70/tn (currently at £69.25/tn on the mid-price).
- UKAs “gapped-up” to the tune of 18% back in mid-December when the Dec-25 contract expired – though spot prices on the secondary market remain at an approximate £2/tn discount.
- Today’s UK electricity generation mix is bullish in nature – specifically, renewables are contributing 31%, thermal at 35% (gas and coal) and low carbon at 19% (nuclear and imports).
- Monthly Day-Ahead averages for January so far are looking very wintry at £104/mwh (or 10.4p/kwh exc. non-energy).