



Fri, 5th Sep ’25
GAS
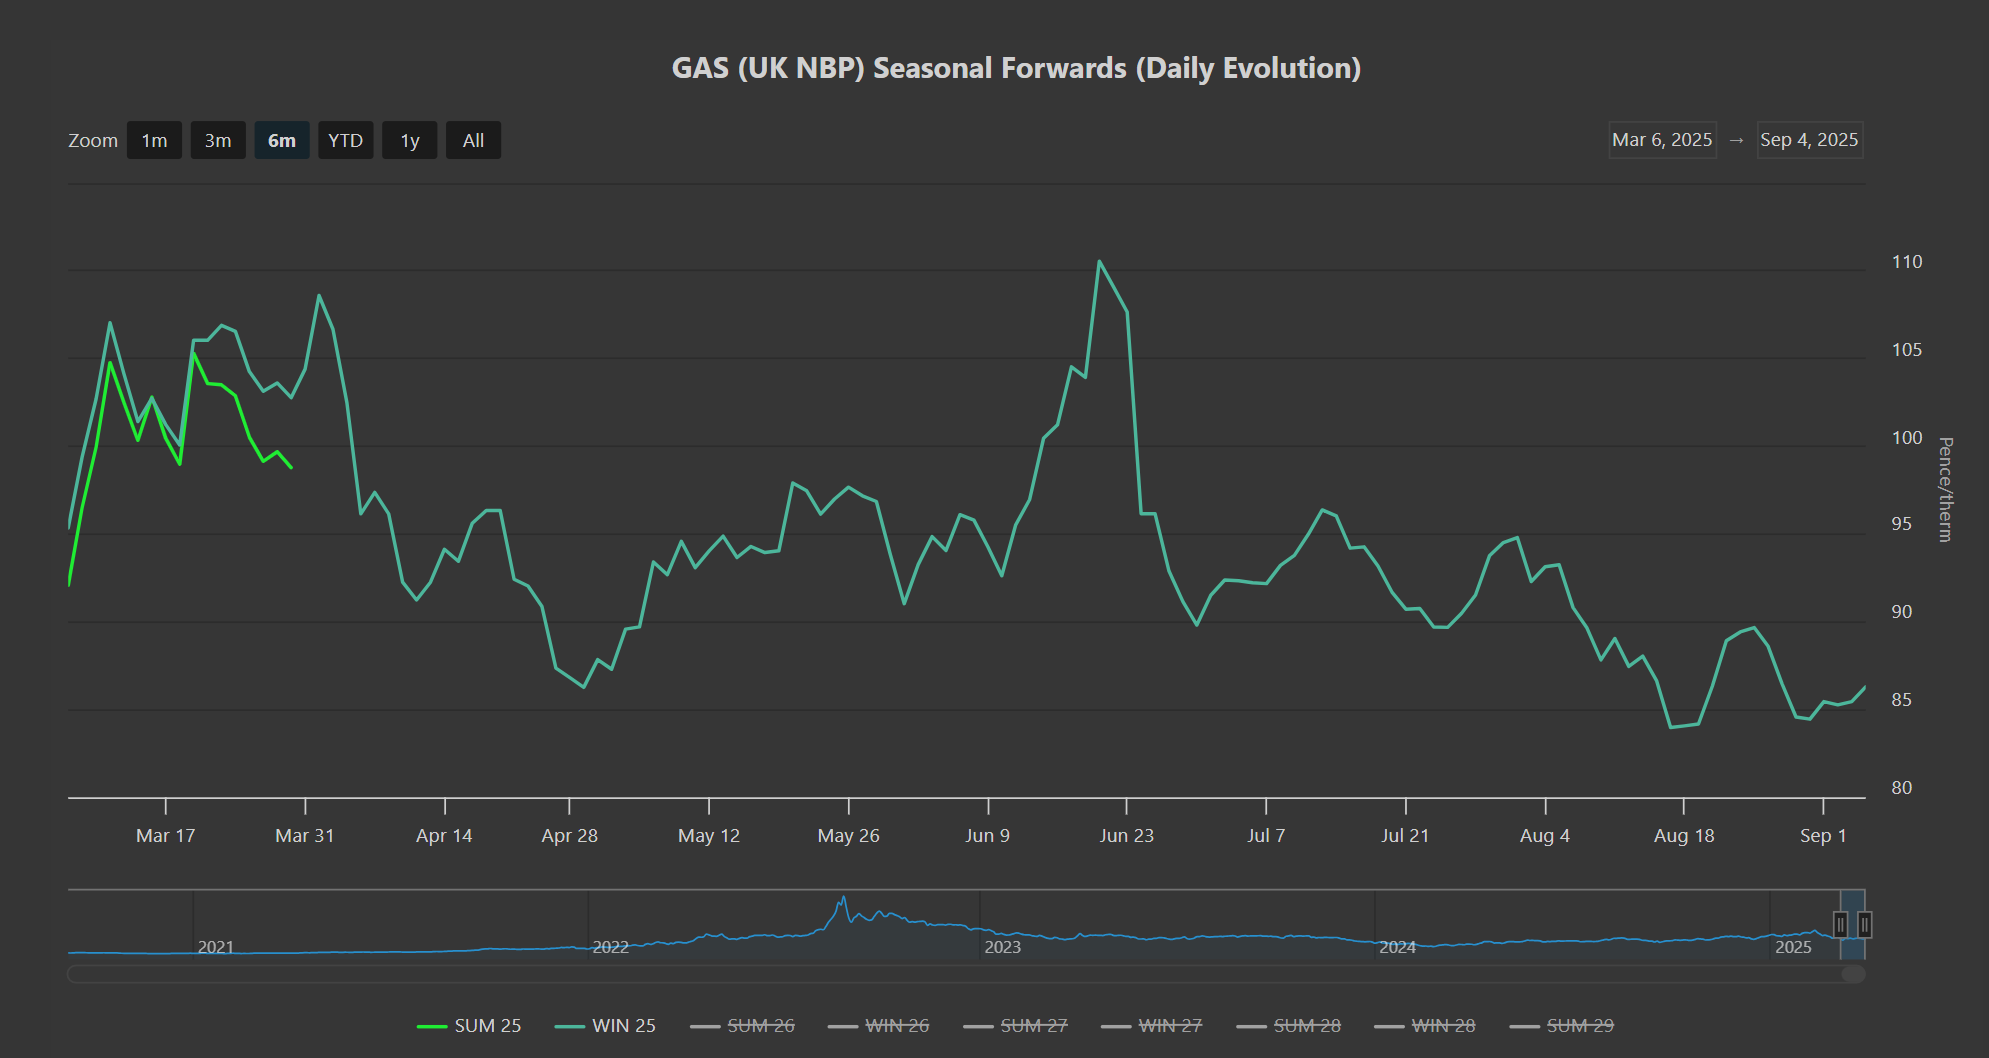
- Notably, and by way of illustrating how volatility has decreased further over the summer period, prices now for Winter-25 delivery are at a 12.5% discount versus the offers we saw for Summer-25 delivery back at the end of Mar ’25 (please see chart below).
- Markets are marginally up today off the back of poor wind outputs, and cooler temperatures forecast for the weekend.
- The main talking point amongst market participants is the impact of Russia into China gas transit – both pipeline (beefing up the existing ‘Power of Siberia’ pipeline) and LNG (the second ever delivery of LNG from the US sanctioned Arctic LNG 2 export terminal in Russia is expected to degasify in the coming days at Beihai import terminal in China).
- On the face of it, more gas flowing into the global system should be a bearish driver regardless of where it’s coming from, or where it’s going – so all eyes are on Trump’s reaction to China shrugging off US sanctions and instead deepening trade relations with Putin.
- Certainly, China’s recent show of force at a parade with Xi Jinping, Putin and Kim Jong-Un front and centre, makes clear that China believes it can weather Trump’s tariffs – so it would seem likely that Russia will continue to deliver more and more gas into China.
- Escalations by Ukraine forces have seen missiles launched at key Russian infrastructure – an oil refinery in Ryazan and an oil depot in Luhansk.
- As such, fears of the extent of Russia’s reprisals are stoking some bullish momentum on near-term delivery – hence today’s supportive tone.
- European storage fullness is now at 79% versus the 5-year average of 89% – with injections slowing (in the main) due to the climax of the Norwegian pipeline maintenance season.
- Any late buyers of Winter-25 delivery are strongly encouraged to get in soon before winter conditions kick-in (and storage injections flatten come October).
- Monthly Day-Ahead averages so far have been at 79p/therm (or 2.7p/kwh exc. non-gas) since the start of the month – so, very low volatility persists.
ELECTRICITY & CARBON
- Prices have firmed a little today in line with firmer gas Forwards.
- On the Carbon side of things, UKAs are increasingly correlated to EUAs (following the “common understanding” reached between the UK/Europe to link emissions markets at the UK-EU summit in London on 19th May).
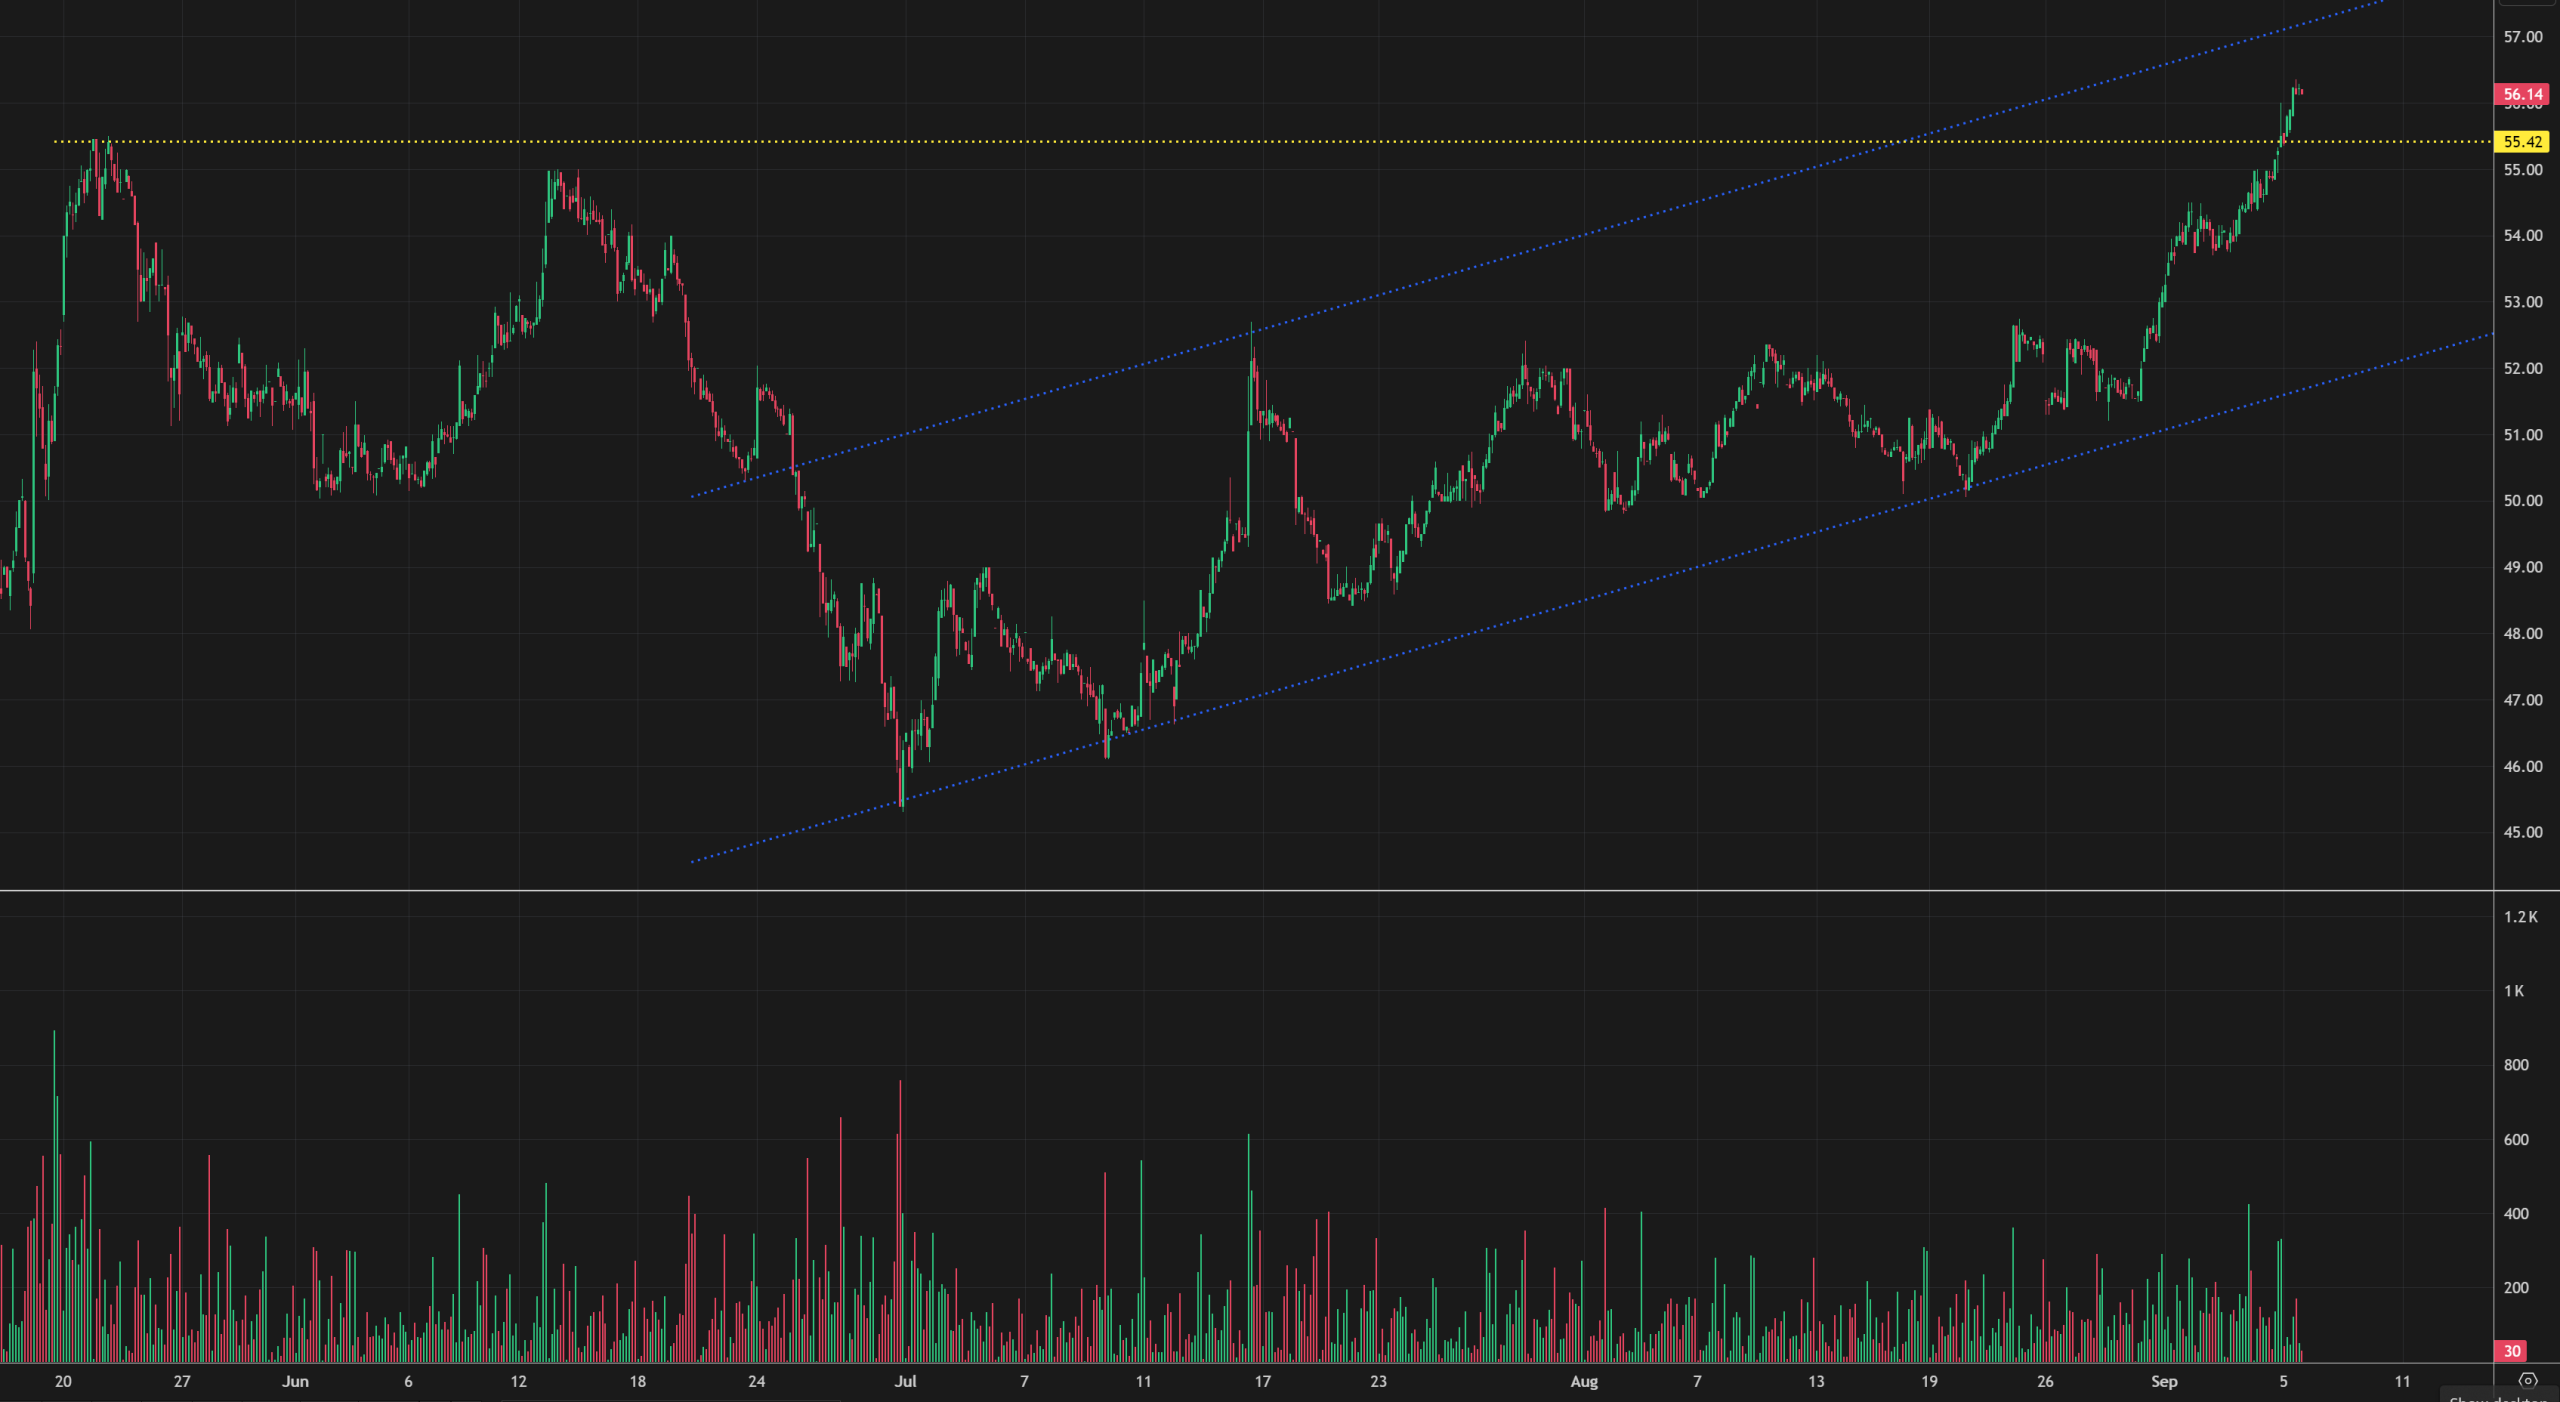
- Dec ’25 UKA benchmark prices have broken to the topside off the back of the impending close to the summer season – prices having broken above further resistance levels and are at £56.16/tn on the mid-price.
- As per the chart below, prices are now observing an upwards trend channel, with the next meaningful resistance level at £57/tn.
- Despite poor wind outputs across Europe, today’s UK electricity generation mix is bearish in nature – specifically, renewables are contributing 42%, thermal at 17% (gas and coal) and low carbon at 22% (nuclear and imports).
- Any late buyers of Winter-25 delivery are strongly encouraged to get in soon before winter conditions kick-in (and gas storage injections flatten come October).
- Monthly Day-Ahead averages for the month so far are at £72/mwh (or 7.2p/kwh exc. non-energy) – which happens to be the Monthly Day-Ahead average for the whole summer to date (reflecting very low volatility this season).