



Fri, 4th Apr ’25
GAS
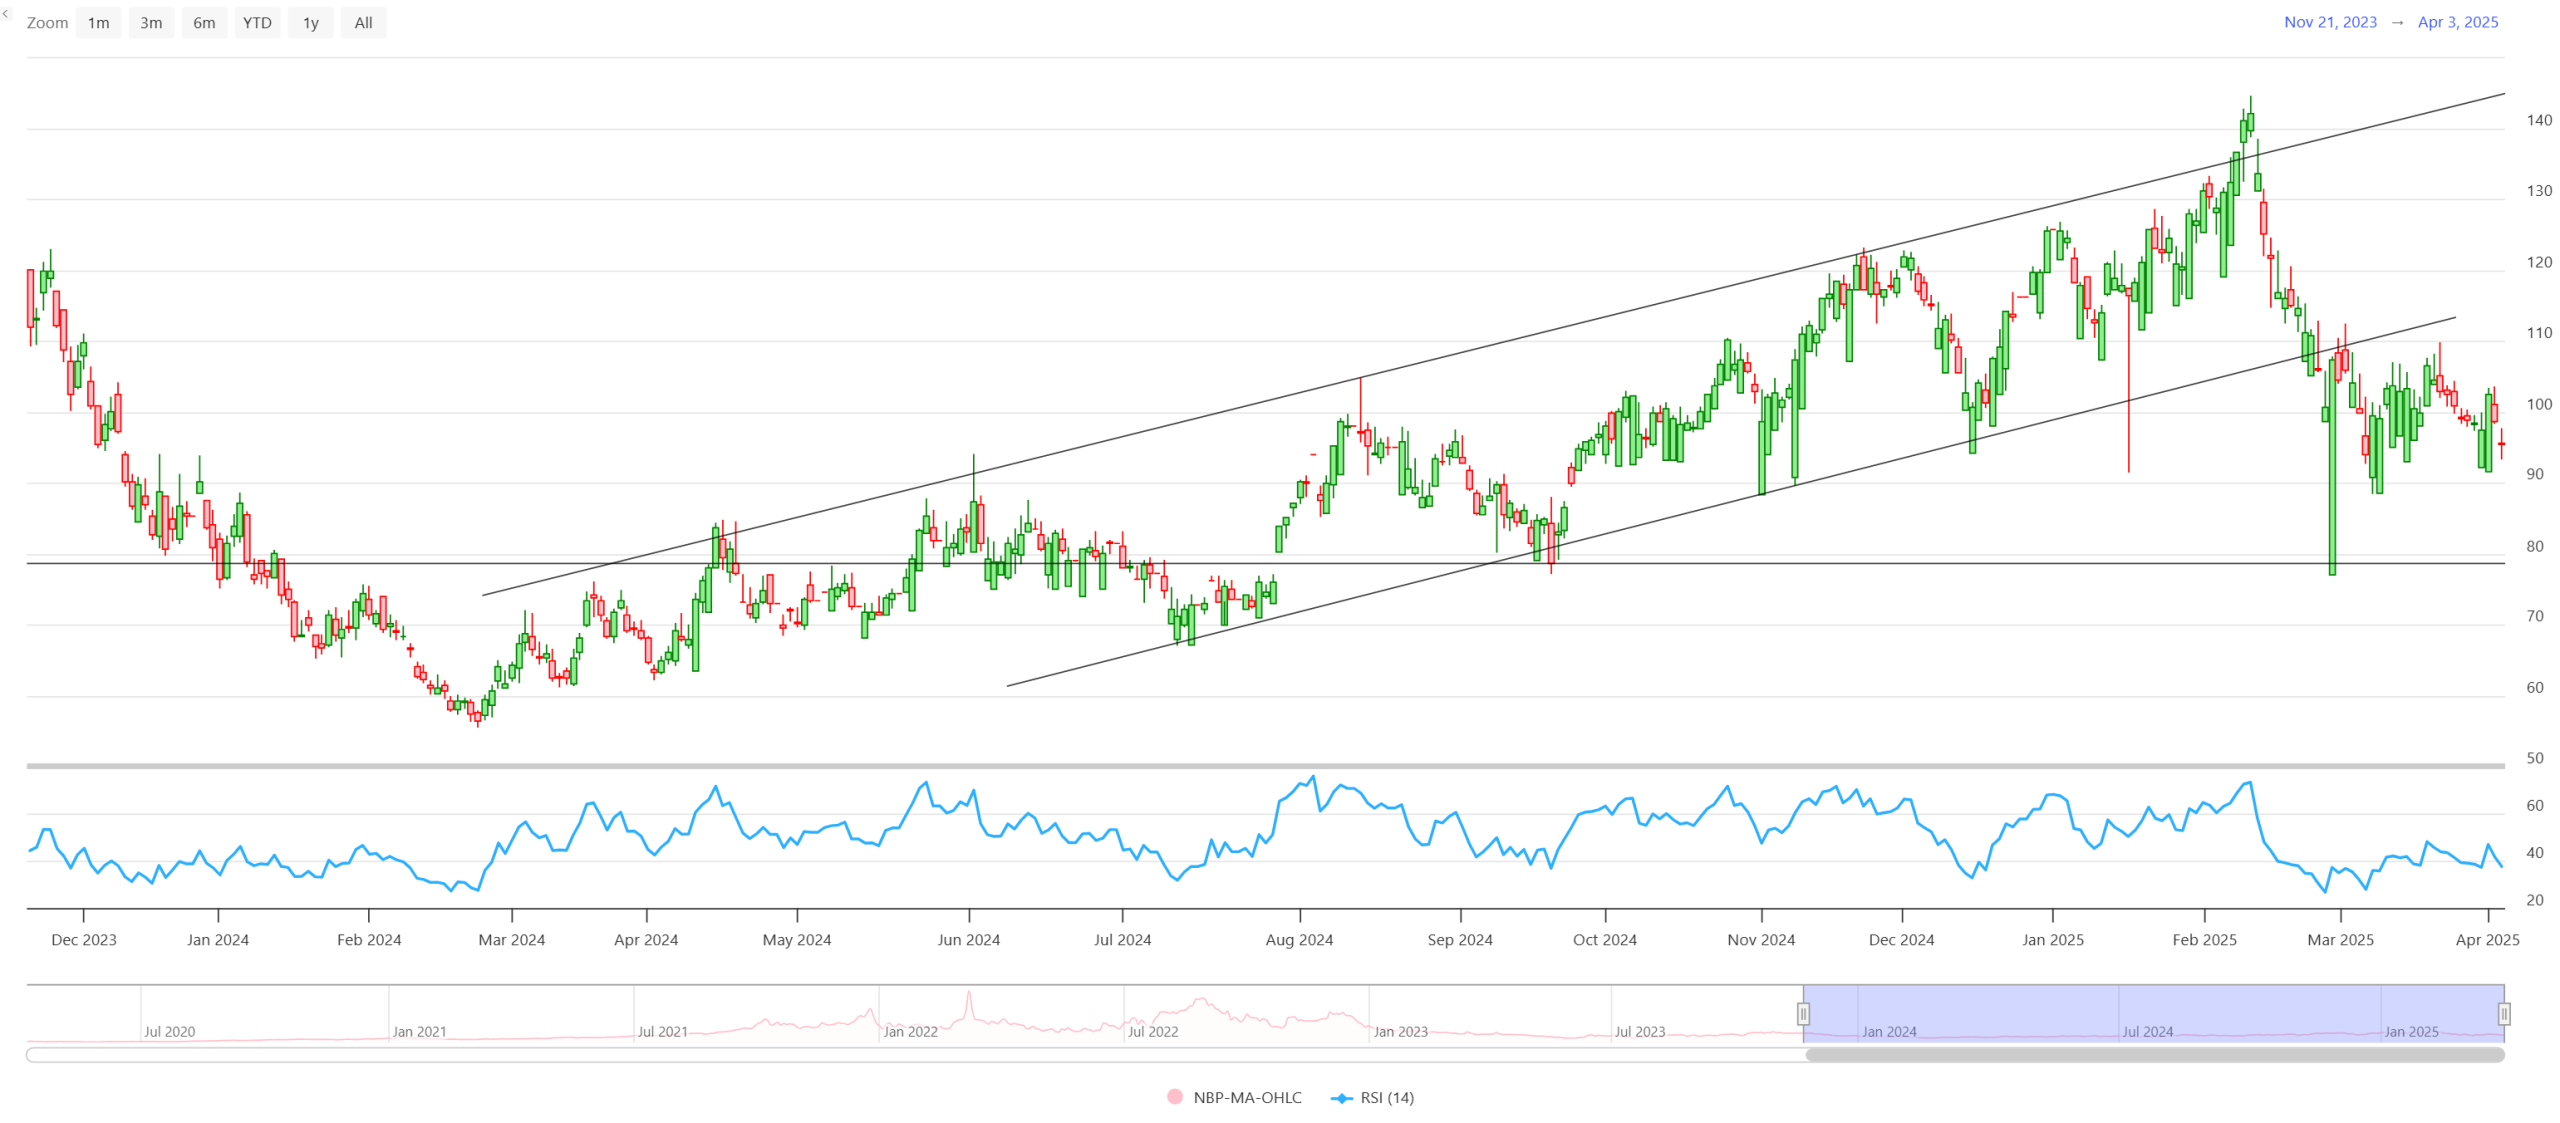
- Notably, Month-Ahead delivery prices observed a rising trend channel (which first formed at the outset of Summer-24) until as recently as late Feb-25 when prices fell out of the bottom, then retested resistance in Mar-25 only to reject to the downside – so, it’s safe to say the bull trend is at an end, and markets are now consolidating within a 30p/therm range, with confirmed support (19th Sep’24/27th Feb’25) at 80p/therm and confirmed resistance at 110p/therm (3rd Mar’25) – please see chart below.
- As such, against a backdrop of global recession fears (following Trump’s tariffs), and summer conditions (warm and windy weather), more downside in the short to medium term would seem likely.
- All that stands in the way of a welcome bear rally are concerns over storage replenishment over the coming months (in time for the mandated 90% fullness by 1st Nov ’25).
- Whilst storage is hovering below the 5-year average (34% versus the 5-year average of 47%), it’s still true to say that levels have started increasing over the last few days with modest injections amid weaker demand off the back of favourable weather.
- Nonetheless, we can’t ignore the impacts of the inevitable Norwegian scheduled/unscheduled outages over the coming months (taking pipeline capacities offline).
- And so we come back to our reliance on LNG imports – which relies on low Asian demand persisting, the JKM spread encouraging cargoes towards Europe, and the timely introduction of new LNG facilities across Europe.
- Across the board, global markets are sliding amid talk of impending global recession, and the associated demand destruction.
- Interestingly, talk amongst less mainstream economists is pointing towards the inevitability of the current situation, with some participants suggesting Trump’s protectionism is a deliberate ploy on the part of the American’s to bring about a much needed recession.
- By the end of 2026, the US needs to contend with massive refinancing – with nearly $10 trillion dollars of Treasury bonds maturing.
- A significant portion of this government debt was issued during the pandemic years when interest rates were on the floor.
- Now, of course, interest rates are back up above 4% – the only way to reduce the yield of the looming refinancing is to put the brakes on the economy.
- Tariffs (and the inevitable slowing of economic activity) are a sure-fire way to achieve contraction.
- So, is Trump’s master plan to lower interest rates in the mid-term, refinance the government debt burden on significantly improved terms (lower interest rates), only thereafter to stimulate the economy with lower interest rates having been achieved?
- Time will tell, of course – though watching America’s benchmark 10-Year Treasury bond will be a clear signal.
- As bond prices rise, yields fall – right now the 10-year Treasury yield has dropped to 3.882% – the lowest level since Oct ’24.
- The yield topped at 4.8% back on 14th Jan ’25 amid hopes that Trump would drive economic activity with tax cuts – which didn’t happen…
- Back in the UK, this month’s gas Day-Ahead averages are at 97p/therm (or approx. 3.3p/kwh excluding non-gas).
- Down the curve (at the time of writing), ALL live periods of delivery are below 100p/therm for the first time since mid-Apr ’24.
- FLEX clients with open volumes are encouraged to consider hedging for periods Winter-25 onwards (given the comparative value on offer).
ELECTRICITY & CARBON
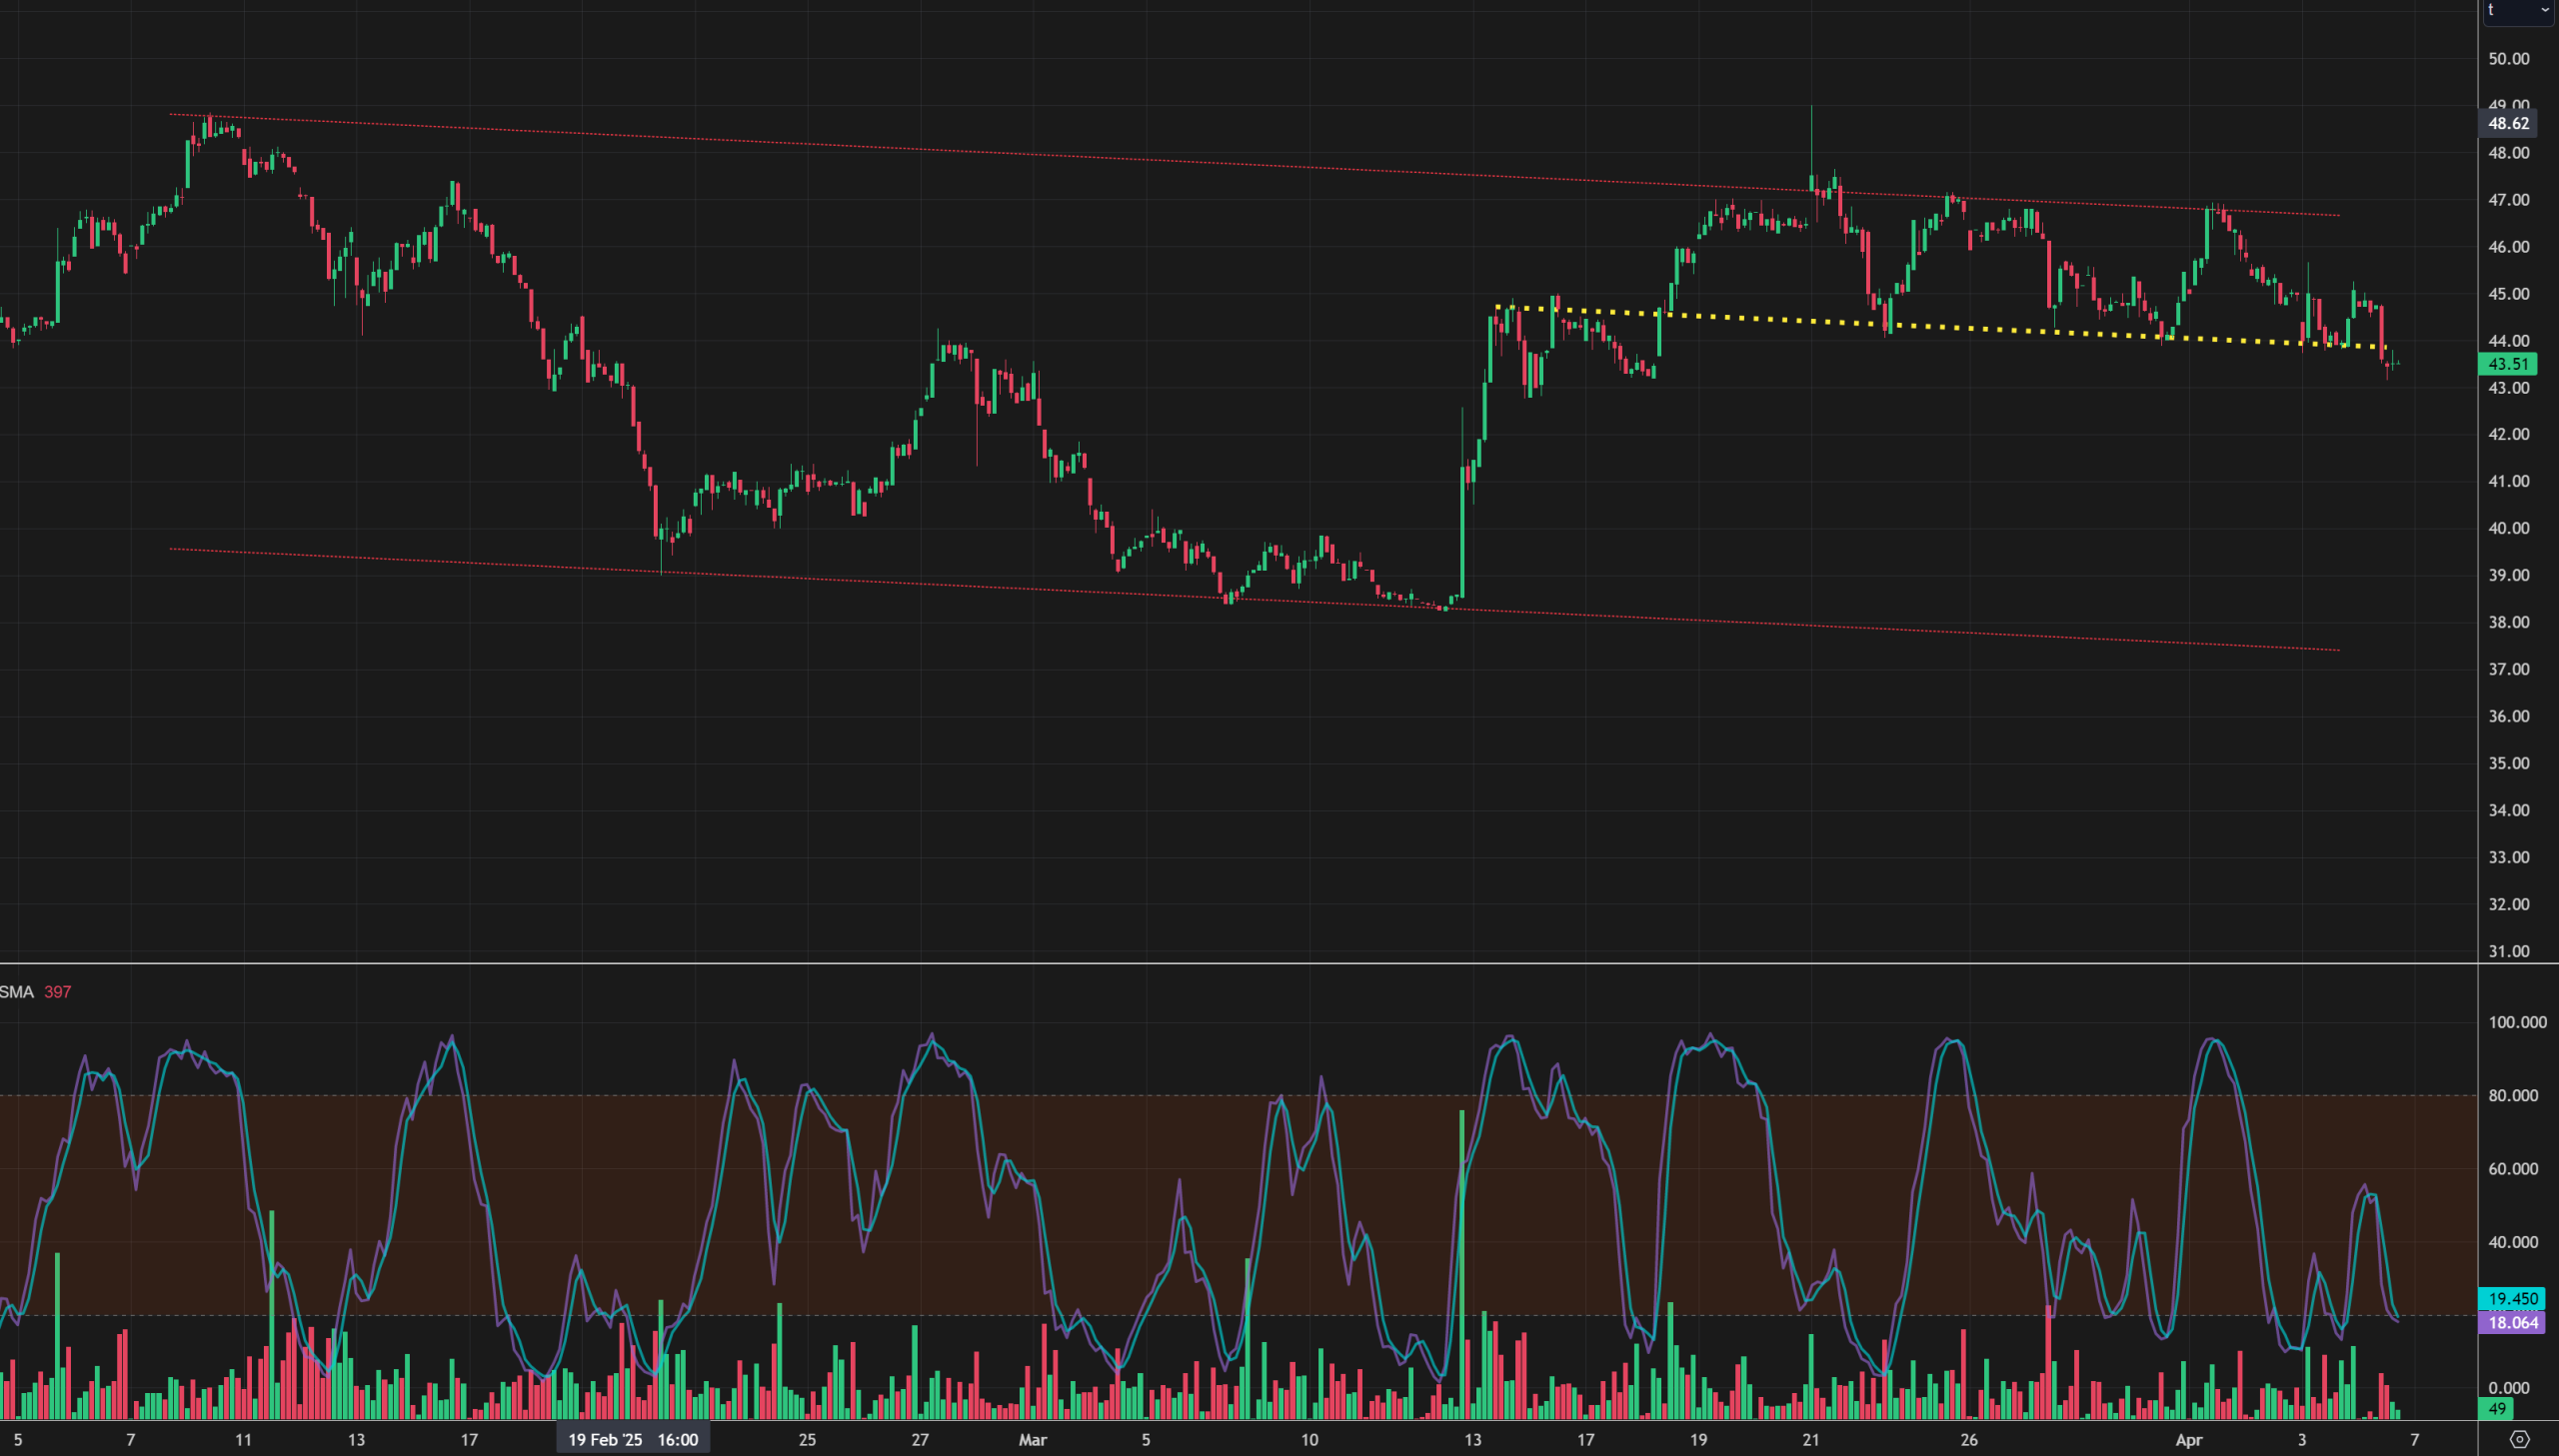
- Like all commodities, electricity is on the slide today with investors running for the door.
- On the Carbon markets, given the correlation to fossil fuels, EUAs and UKAs are looking heavy – not great news for the institutional investors/speculators who remain net long!
- If the slide picks up momentum, stop losses will be wiped out and the bear rally will pick up speed.
- Compliance buyers will be eyeing up value at £38/tn at the bottom of the current bearish trend channel ( see chart below).
- Today’s UK electricity generation mix is very bearish in nature, with renewables contributing 65%, thermal at 4% (gas and coal) and low carbon at 20% (nuclear and imports).
- So far this month, electricity Day-Ahead averages are on target to achieve £73/mwh (or approx. 7.3p/kwh excluding non-energy).