



Fri, 29th Nov ’24
GAS
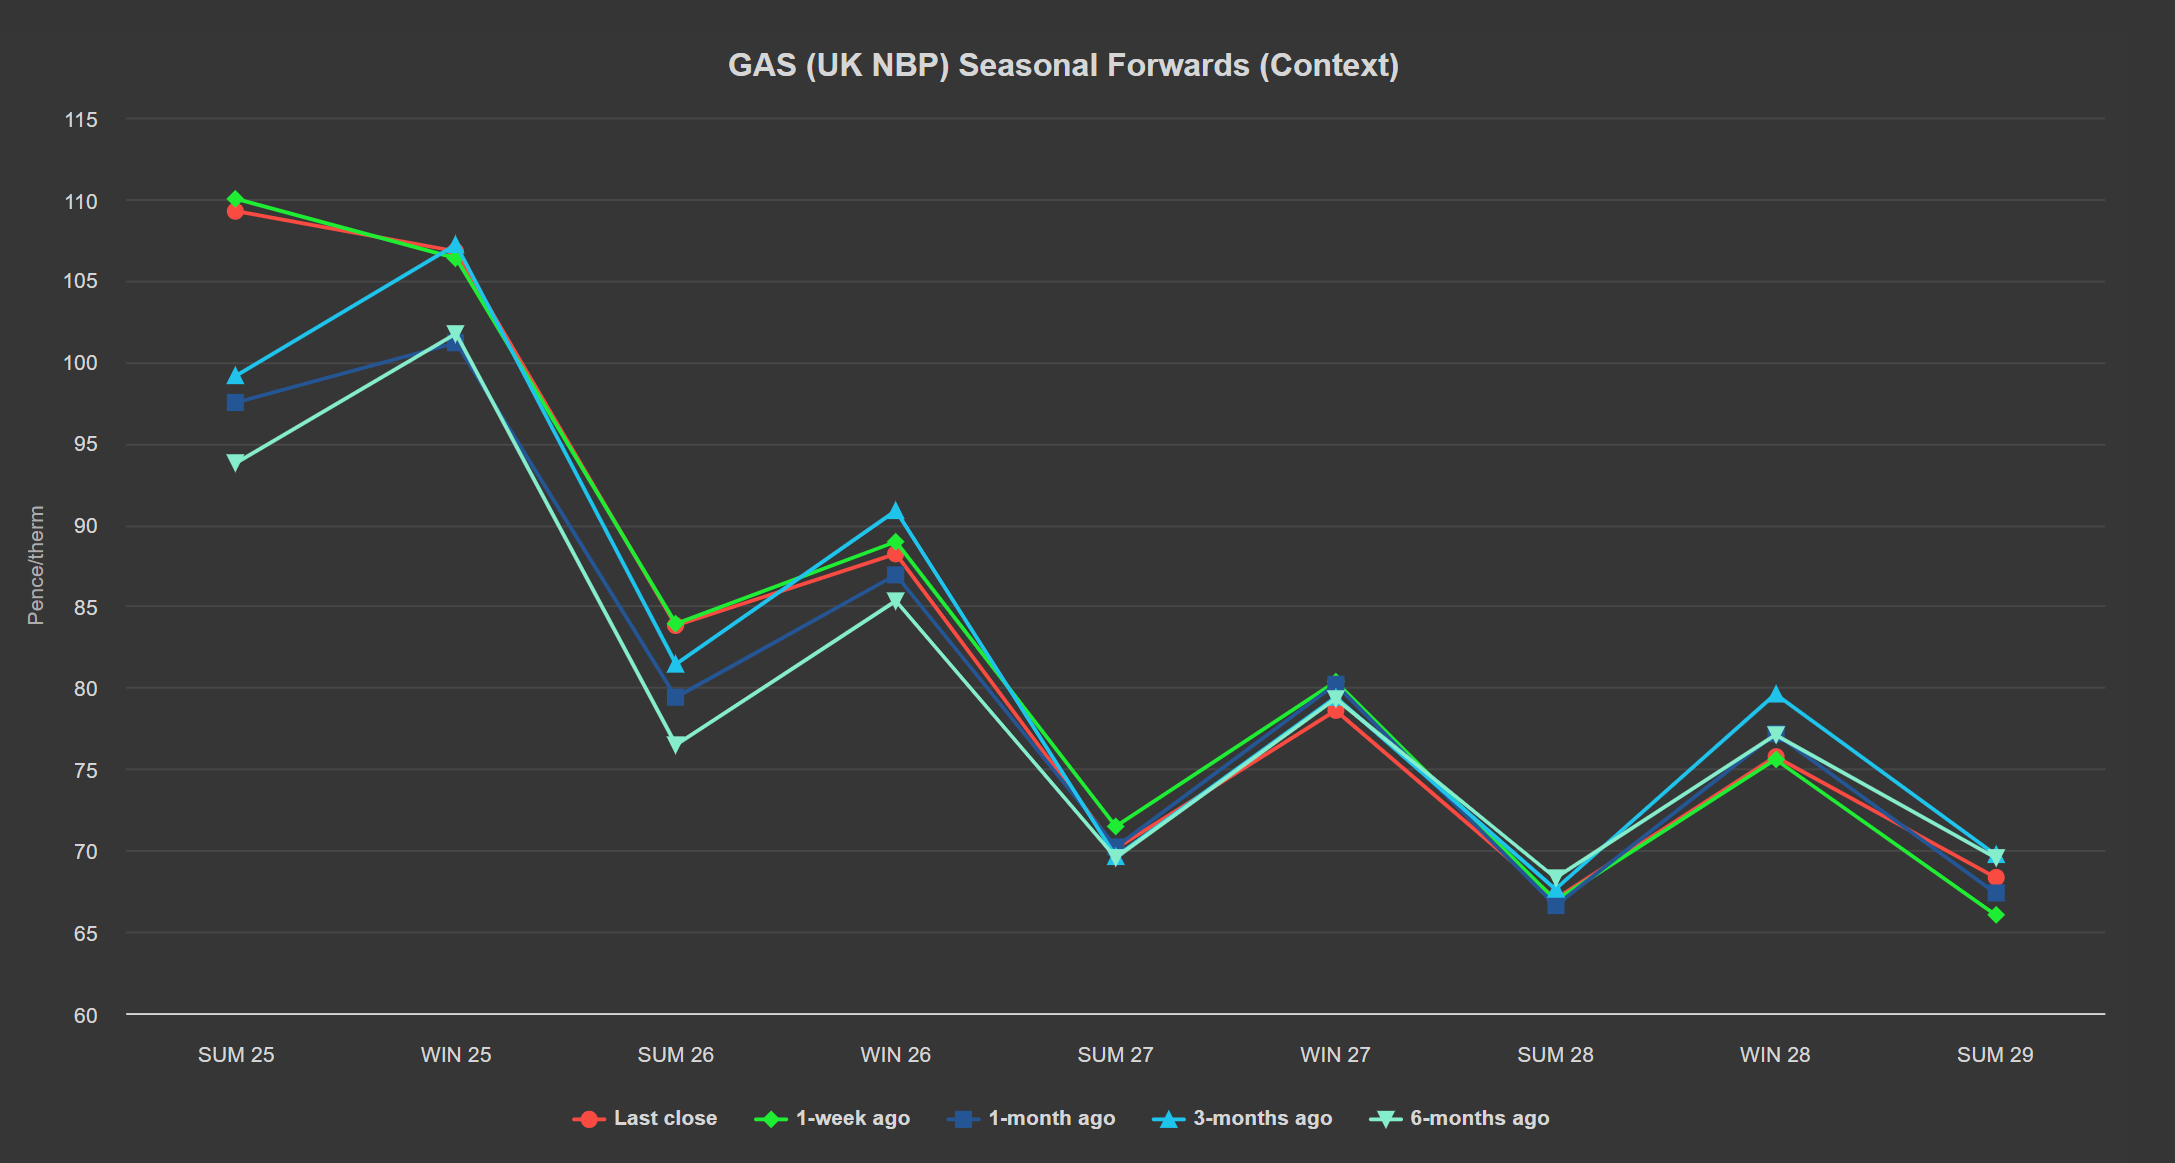
- Notwithstanding supportive drivers (Ukraine/Russia transit deal due to end; lower temperatures meaning significant storage withdrawals; ongoing geopolitical uncertainty), front Seasons are marginally down on the week (see chart below).
- Prices are drifting sideways again today amid the impacts of the Israel/Hizbollah ceasefire which is just about holding; warmer temperature forecasts and improved wind outputs limiting gas-for-power burn; gas withdrawals slowing.
- In short, markets have found equilibrium for the time being – neither bears nor bulls have the upper hand.
- Nonetheless, UK prices will likely remain at a premium versus Europe’s as the winter progresses – otherwise, we’ll be left high and dry where LNG arrivals are concerned.
- This premium is always exacerbated by structural problems in the UK’s gas system resulting in high transmission costs and, of course, a lack of storage compared to Europe – meaning the UK needs to offer a much higher price to secure supply.
- Monthly Day-Ahead averages for Nov-24 achieved 110.267p/therm (or approx. 3.762p/kwh excluding non-gas).
ELECTRICITY & CARBON
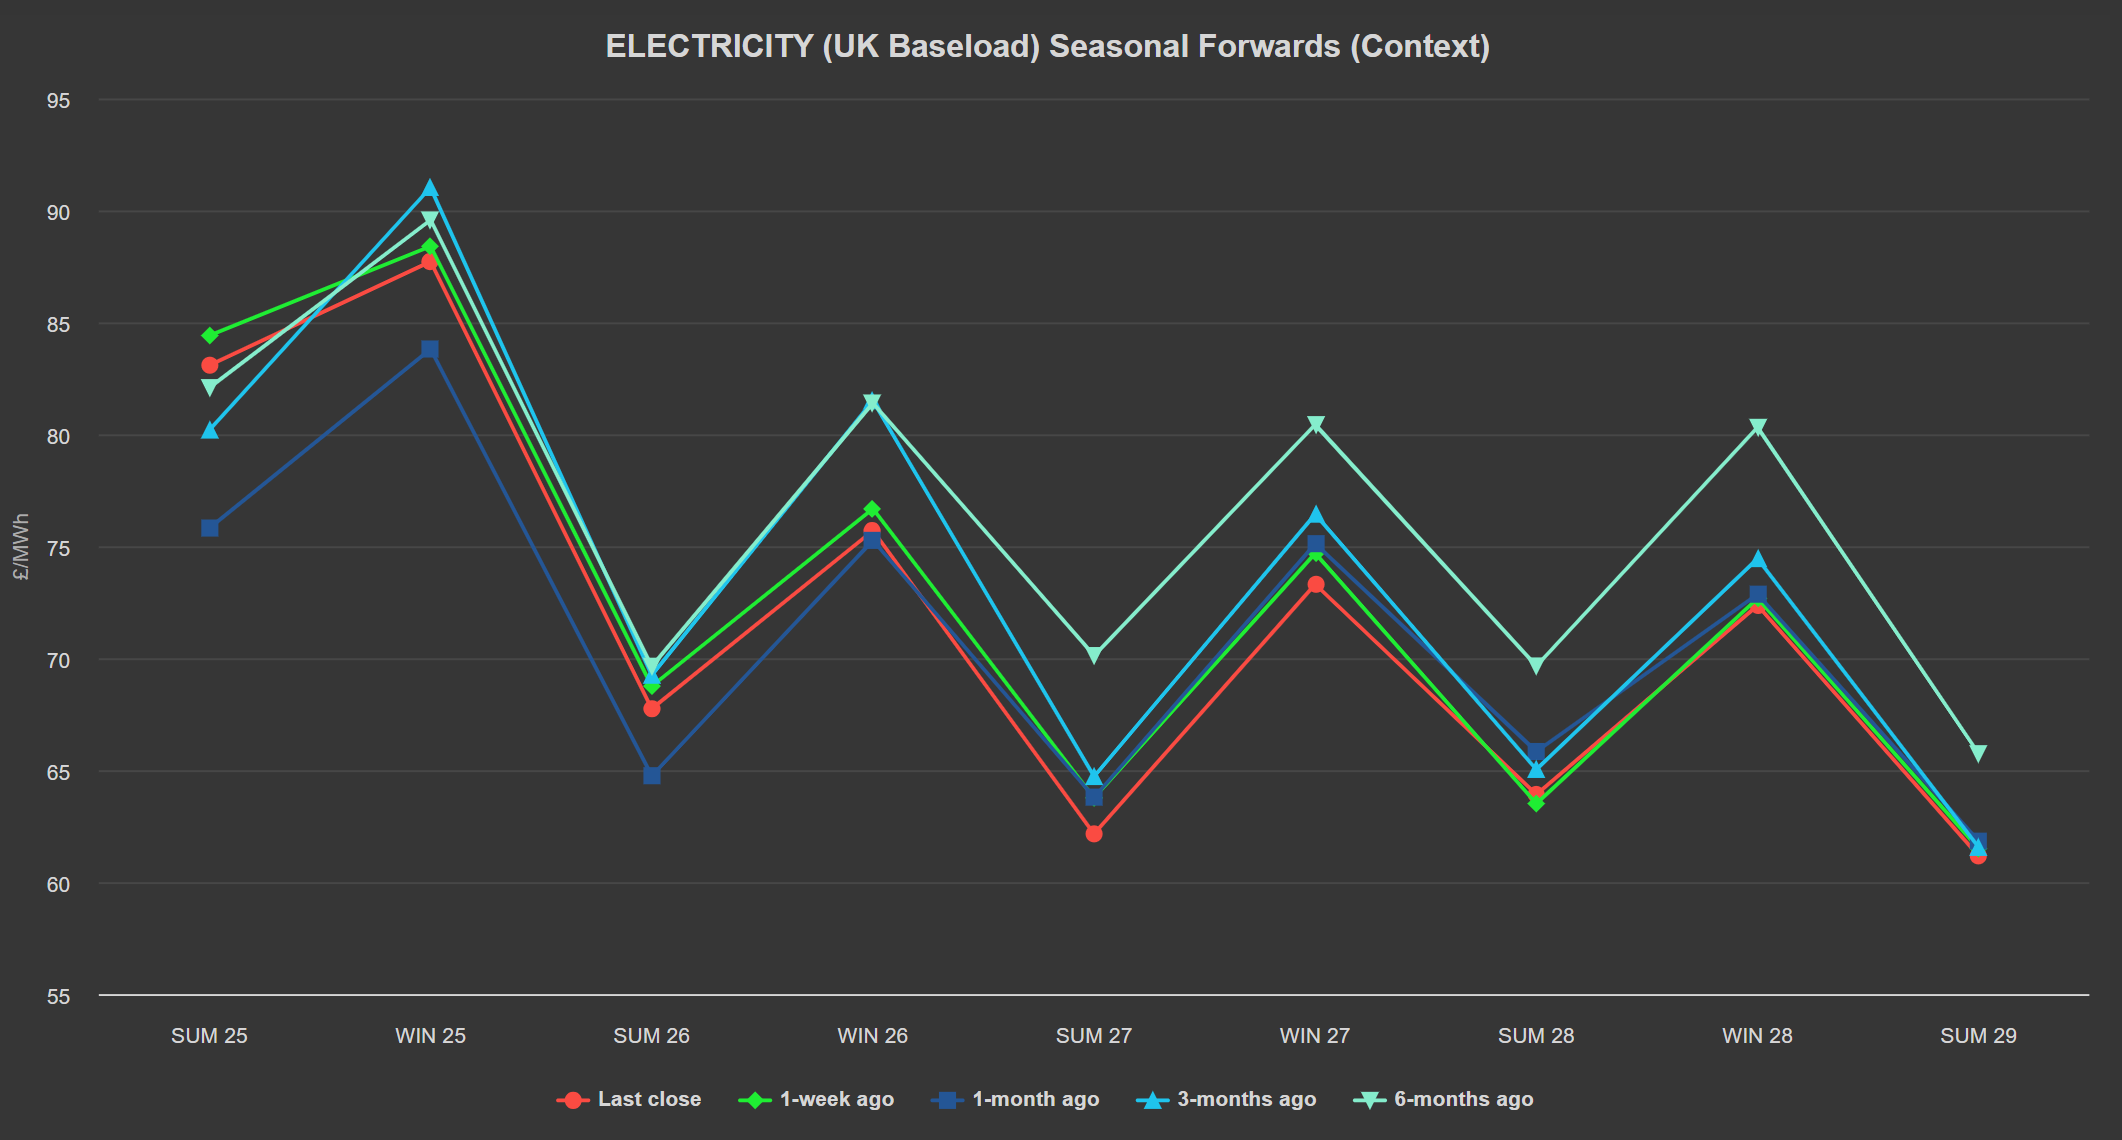
- On the Carbon markets, EUAs edged lower yesterday with the Dec ’24 benchmark closing at €67.63/tn after losing 1.23% on the day.
- It is being dragged down by slightly lower gas prices but fundamentally, we have seen lower emissions over the past days in the power sector thanks to above average wind levels.
- This is set to continue next week, reducing demand in the short-term.
- As we’d been predicting, UKAs saw another rally southwards beginning 21st Nov dropping as low as £35.56/tn yesterday on the mid-price.
- Prices have since risen to £36.65/tn off the back of Compliance buyers bargain hunting at these low levels.
- The UK’s electricity generation mix is bearish in nature today with renewables contributing 50%, thermal at 29% (gas and coal) and low carbon at 14% (nuclear and imports).
- Monthly Day-Ahead averages for Nov-24 achieved £97.945/mwh (or 9.79p/kwh excluding non-energy).