



Fri, 28th Jun ’24
GAS
- Both near- and far-term delivery prices traded sideways yesterday, generally closing (very marginally) down on the day.
- Fundamental key drivers are mixed, with a two-day extension of the Teesside outage on the bullish side, and on the bearish side, a much looser UK balance is expected next week – enabling storage injections.
- Norwegian exports have been rerouted from Europe to the UK, with Vesterled pipeline flows having jumped up by 20mcm/d.
- The Teesside outage is likely to complete over the weekend bringing 10mcm/d capacity back online.
- Lower temperatures for next week means a higher gas-for-power demand starting Monday (up by 12mcm/d).
- All these factors combined should mean our balance will be looser (due to the expected higher Norwegian exports and increased domestic production over the weekend).
- This morning, prices are marginally down again off the back of a long system (supply outstripping demand forecast).
- Summer conditions have allowed injections into European MRS (mid-range storage) with the latest figure now at 76% versus the 5-year average of 62%.
- LNG arrivals to Europe/UK are very thin on the ground with Asia taking the lion’s share to generate electricity for cooling demand – at the time of writing, the UK is only expecting one LNG vessel to degasify in early-to-mid-July.
- The scarcity of LNG import is fundamentally supportive – market bears will be hoping to see higher LNG arrivals toward the back-end of Summer-24 (to coincide with the second-half of European/UK scheduled gas maintenance).
- Otherwise, withdrawals from storage may be required (subject to weather impacts and associated demand).
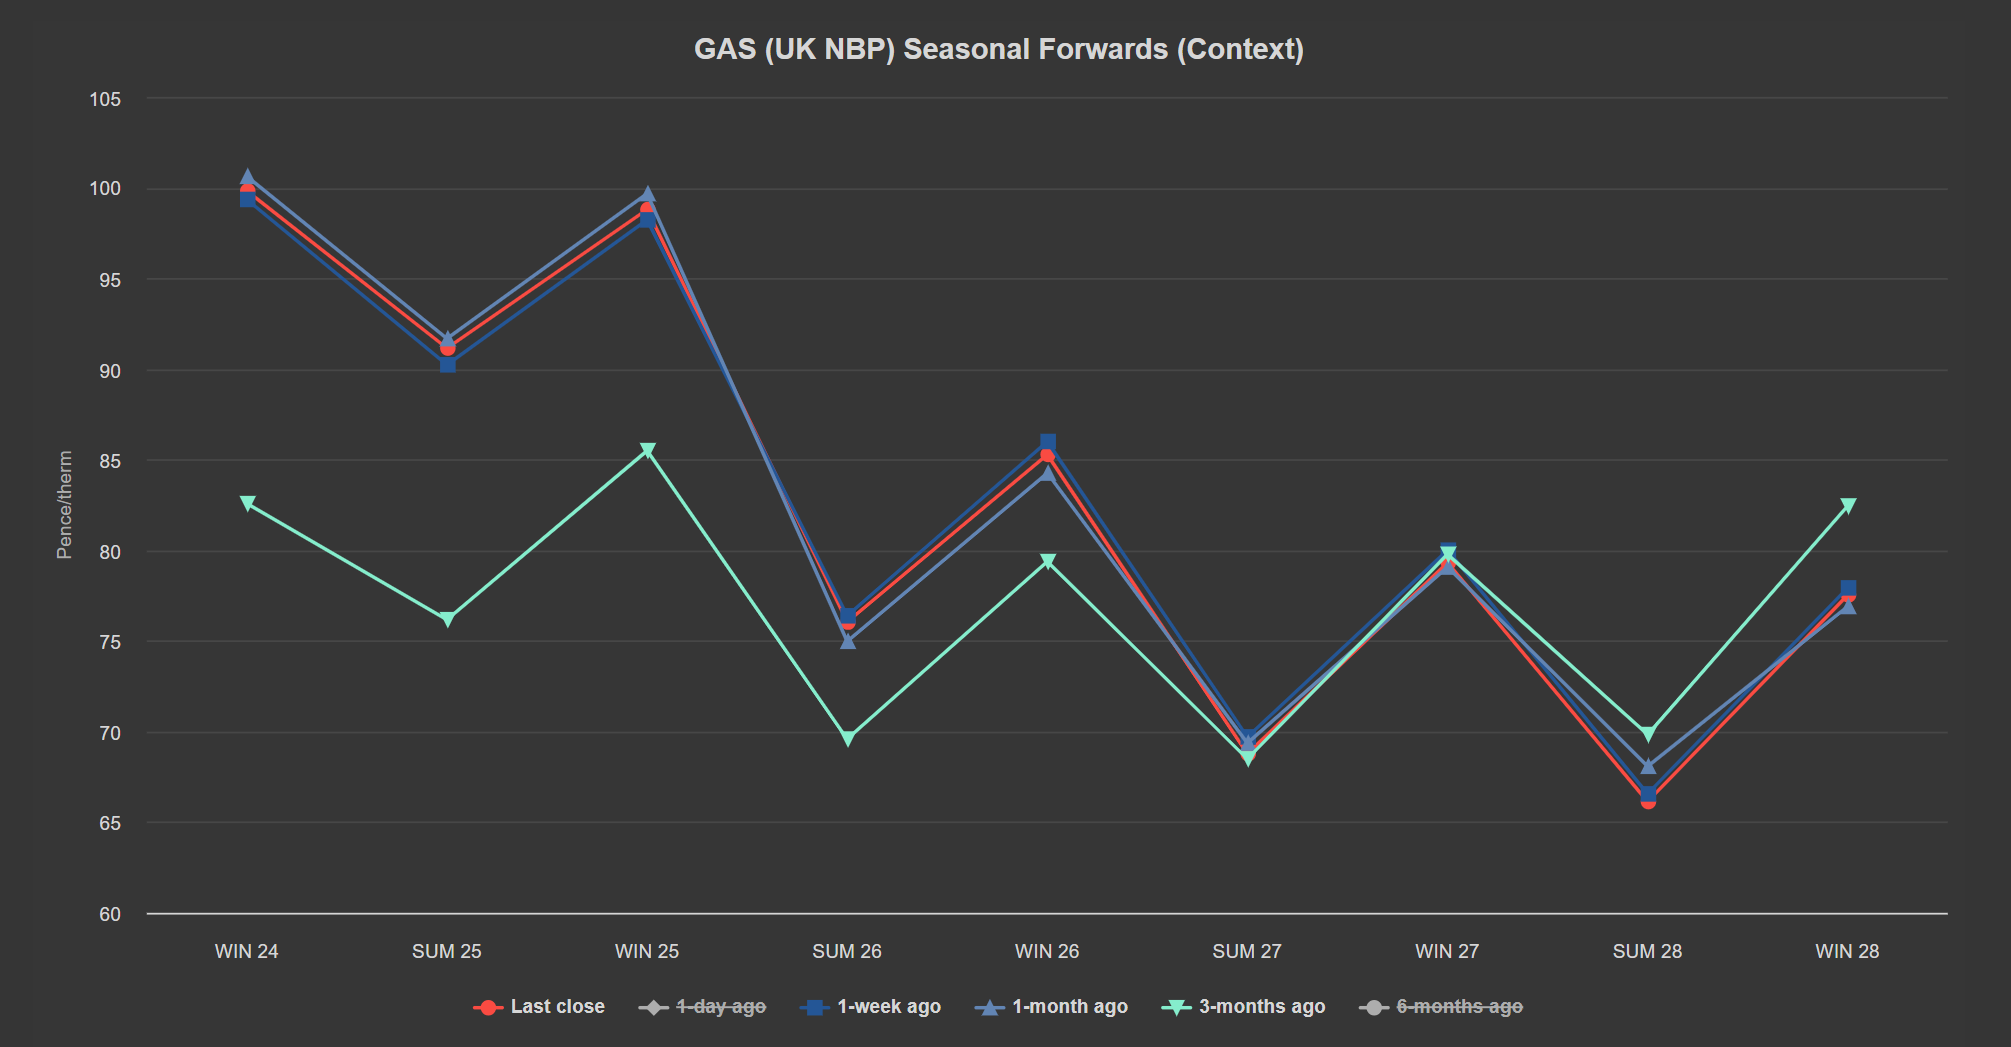
- In short, whilst Seasonal Forwards remain up versus 3-months ago, they’re relatively unchanged versus 1-week/1-month ago (see chart).
- We’re 89 days into Summer-24 (95 days remaining) with the onset of the 2nd half of Summer-24 only a few days away.
- Europe remains on track to achieve 100% storage levels by Winter-24 (early Oct ’24) – though improved LNG import would ease supply/demand tensions.
- Monthly Day-Ahead averages are on target this month to achieve 82p/therm (or circa. 2.8p/kwh excluding non-gas).
- Looking to the continent, European near-term delivery prices fell as expected yesterday – driven down by a combined rise of wind and solar generations.
- Next week will see mixed fundamentals – weather forecasts point toward stronger wind outputs offset by a drop in solar production early in the week.
- Noise aside, fundamental key drivers remain comfortable.
- On the Carbon markets, EUAs continued their downtrend yesterday ending the day at 66.67€/t, -0.26€/t from Wednesday.
- Prices could now head toward the 60€/t mark driven in the main by speculators progressively building back a significant short position.
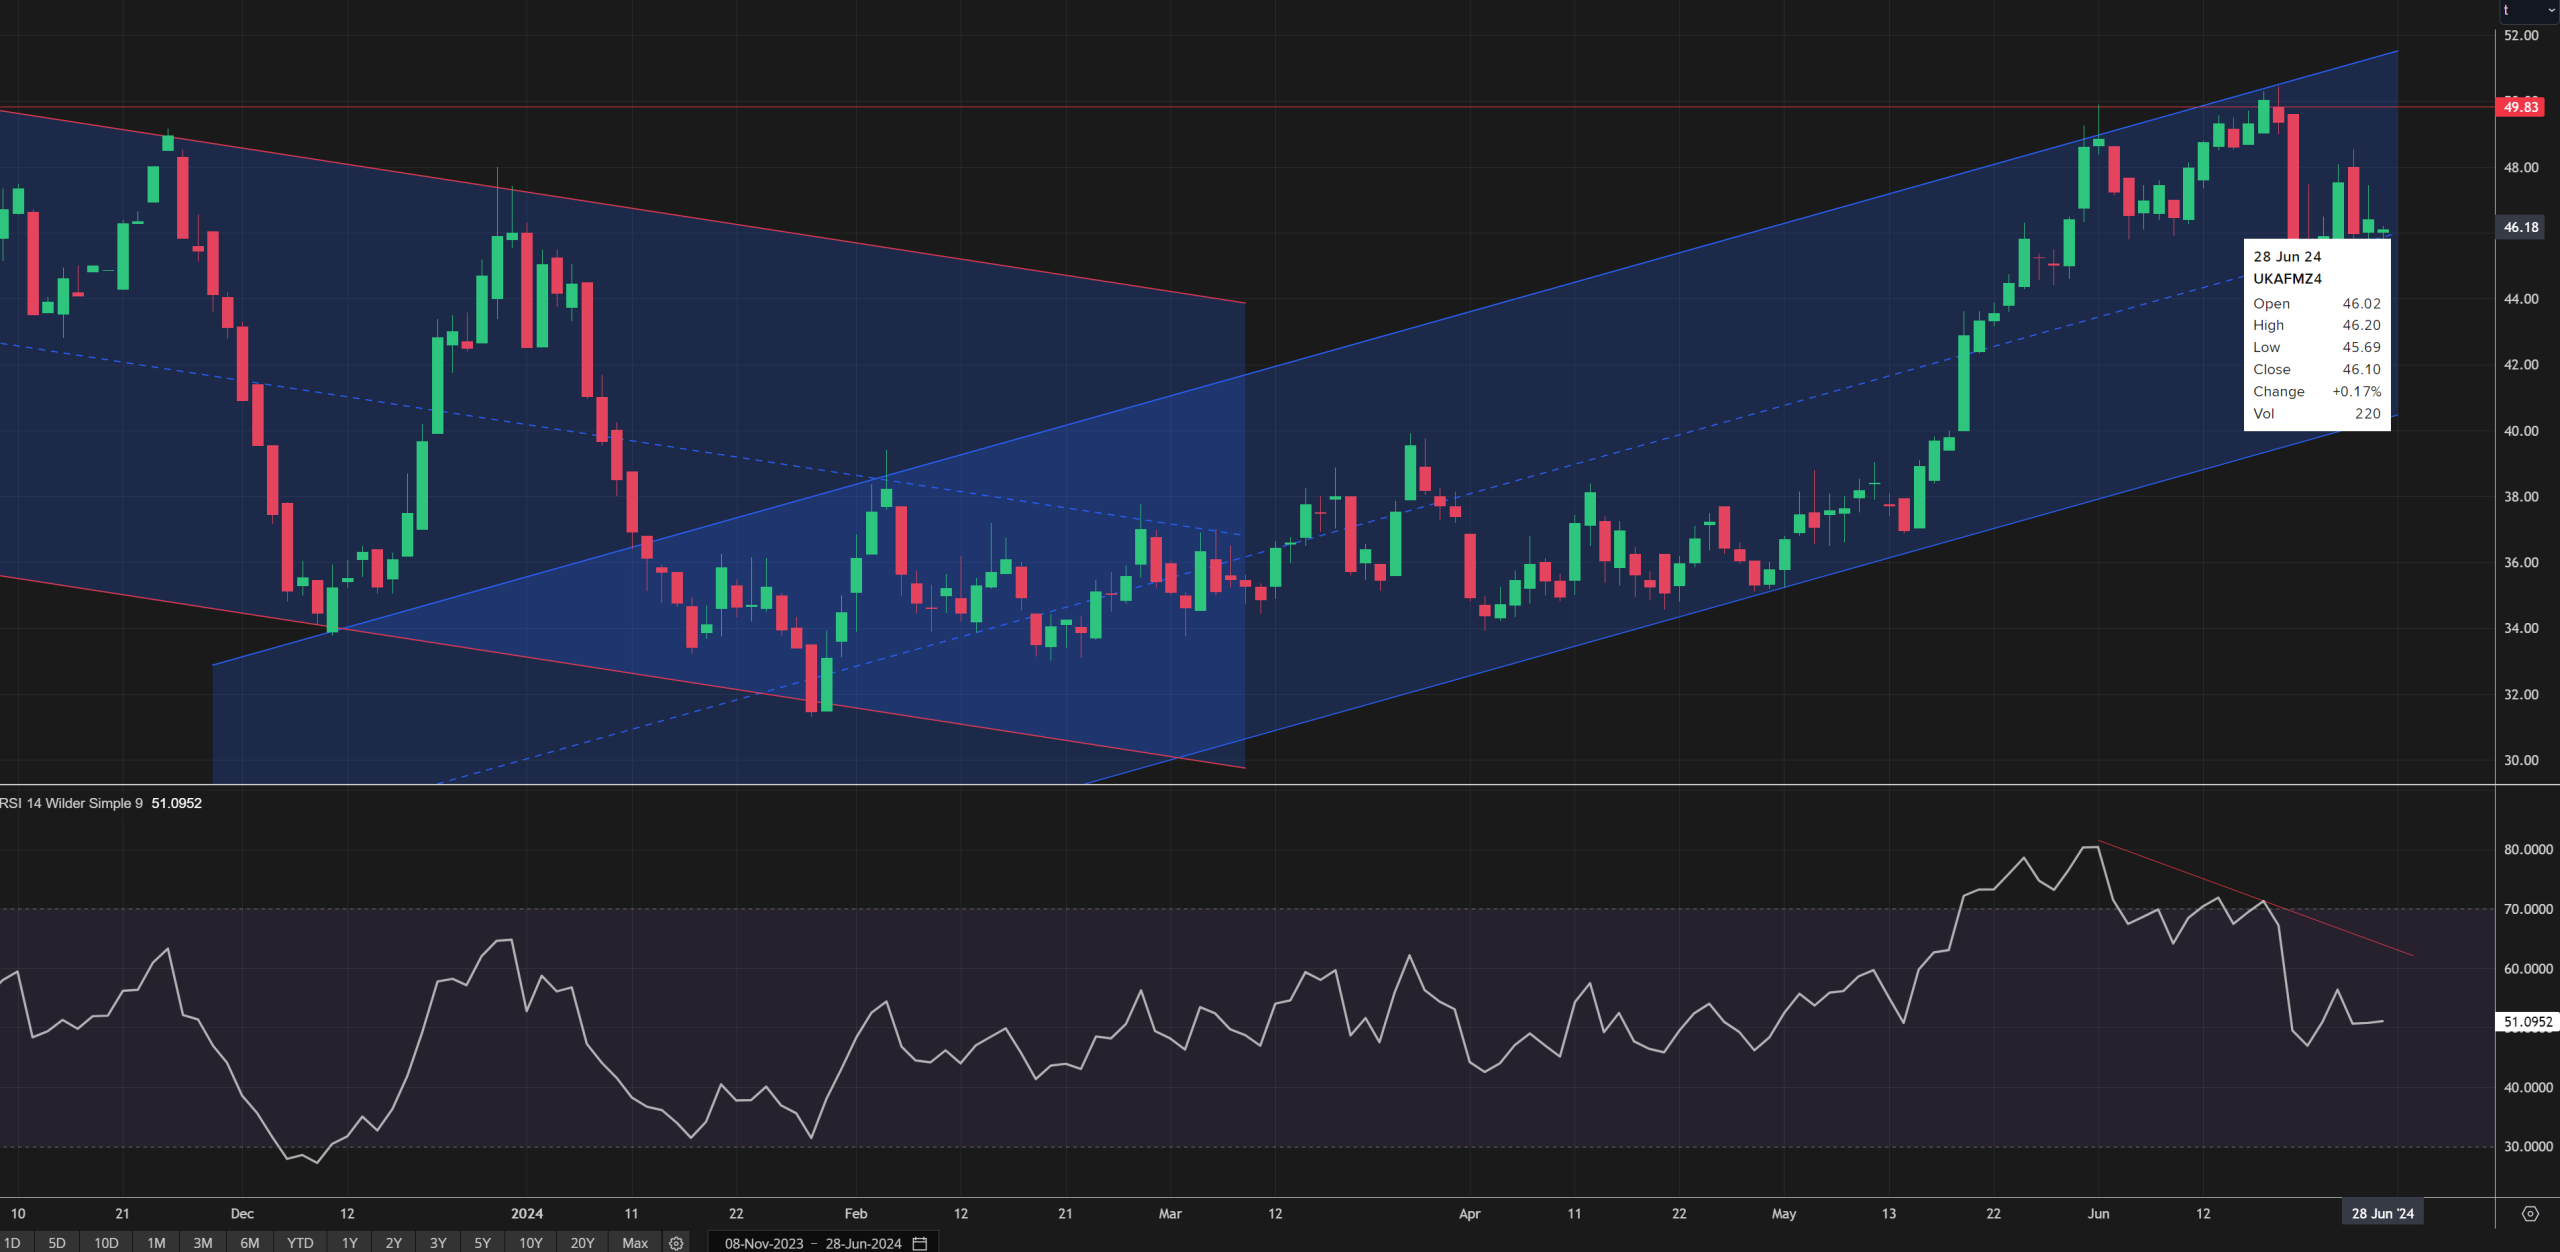
- Back in the UK, UKAs (UK Carbon Allowances) followed our prediction that prices were due to fall as indicated by RSI divergence (see chart) – now trading at circa. £46/tonne.
- Prices are now in a confirmed ascending trend channel testing the mid-line (see chart) – congestion is building at £40/tn as a strong area of support – so a retest of this level will likely result in a bounce.
- Our electricity generation mix is bearish in nature today with renewables contributing 61%, thermal at 10% (gas and coal) and low carbon at 19% (nuclear and imports).
- Electricity monthly Day-Ahead averages are on target this month to achieve £71/mwh (or 7.1p/kwh excluding non-energy).