



Fri, 26th Jan ’24
GAS
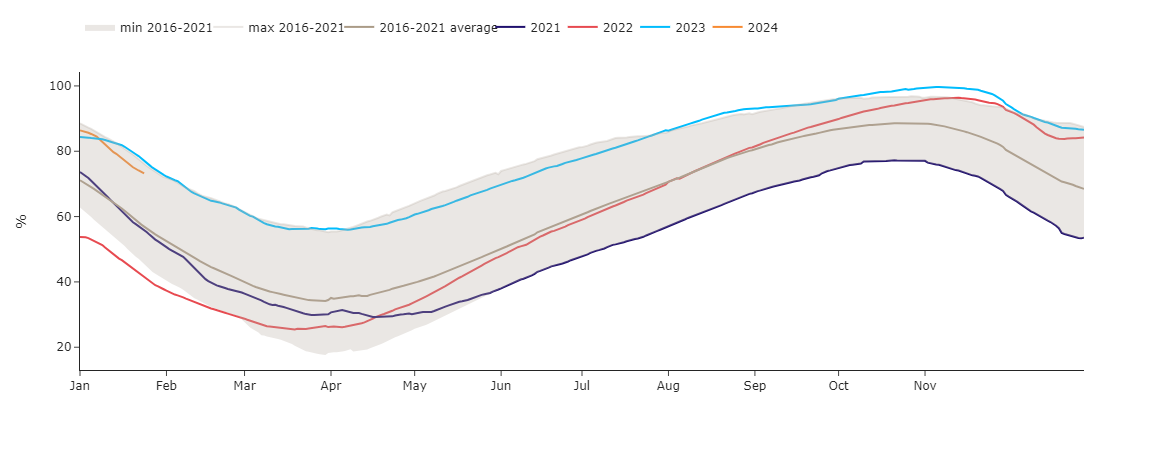
- Notably, European storage remains toward the upper envelope of the 8-year range (see chart).
- At this morning’s open, near-term delivery contracts are down off the back of high wind outputs (limiting withdrawals intended for gas-for-power burn).
- Nonetheless, the UK gas system is still marginally short (demand outstripping supply) following unscheduled maintenance at Barrow terminal which has been extended until Sunday – with UKCS (UK Continental Shelf) flows consequently down 13%.
- UK demand is, however, gradually falling with the onset of increasingly mild and windy weather (reducing heating demand).
- Temperatures are likely to remain above seasonal norms for the coming weeks, sustaining bearish pressure (with the sharp-end of Winter-23 surely now in the rearview mirror).
- Accordingly, Summer-24 prices are increasingly soft given expectations of high storage left in the tank at winter’s end.
- Geo-political risk persists in the form of Middle East escalations and lingering worries over supply disruption in the Red Sea/Suez Canal (limiting downside).
- Monthly Day-Ahead averages are on target this month to achieve 76p/therm (or 2.6p/kwh).
ELECTRICITY
- Our generation mix is very bearish with renewables at 63% and gas-for-power burn at 6%.
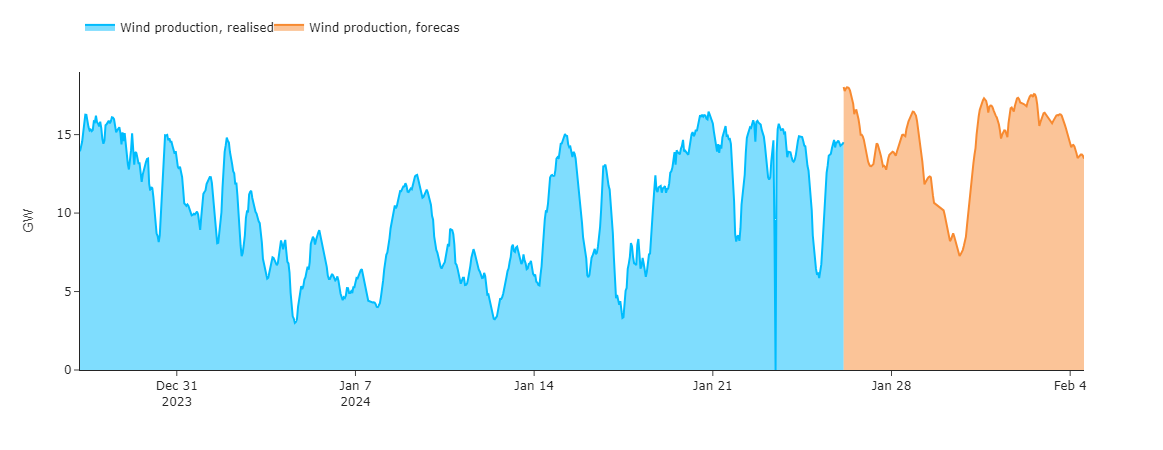
- Wind outputs are strong and forecast to remain so until early Feb (see chart).
- Looking to the continent, European near-term delivery dropped yesterday, weighed by forecasts of weaker demand and improving renewables outputs.
- Improving French nuclear availability and temperatures across NW Europe around 6°C above seasonal norms early next week will likely keep markets under pressure.
- Red Sea risk notwithstanding, market softness can be attributed to comfortable supply/demand dynamics – robust supply, high gas stocks and demand destruction.
- UK electricity monthly Day-Ahead averages are on target this month to achieve £73/mwh (or 7.3p/kwh).