



Fri, 26th Apr ’24
GAS
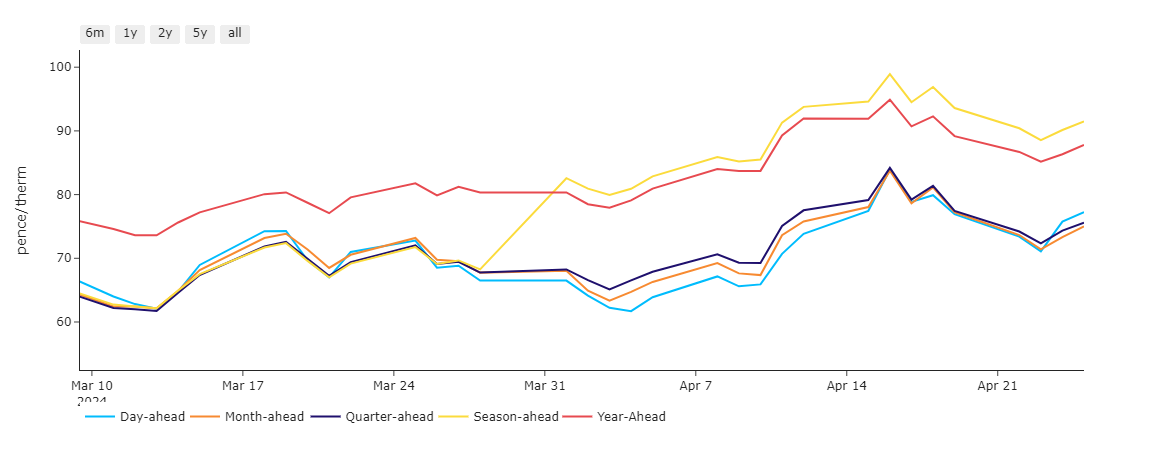
- UK NBP gas mirrored European markets yesterday – a little bullish off the back of supply tightness.
- Season-Ahead is at a marginal premium to Year-Ahead, though Day/Month/Quarter-Ahead are at parity and at circa. 17% discount versus Winter-24 (see chart).
- However, into the weekend, total demand is forecasted down by 44mcm/d (million cubic metres per day) off the back of rising temperatures and strengthening wind speeds.
- Near-term delivery is on the slide today, in the main due to falling demand.
- Encouragingly, LNG arrivals to the UK/Europe are circa. 10% above the 30-day average (easing worries over supply).
- Unfortunately, production at Freeport LNG remains low with ALL three trains still anticipated to require unscheduled maintenance.
- As we reported last week, Freeport looked to have overcome technical problems – however, problems persist.
- Geopolitically, there’s very little noise out of the Middle East – be it news of escalation or peace negotiations – as such, risk of another flare up will continue to offer price support.
- All in all, a mixed bag – hence the sideways price action.
- Monthly Day-Ahead averages are on target this month to achieve 72p/therm (or 2.4p/kwh).
ELECTRICITY & CARBON
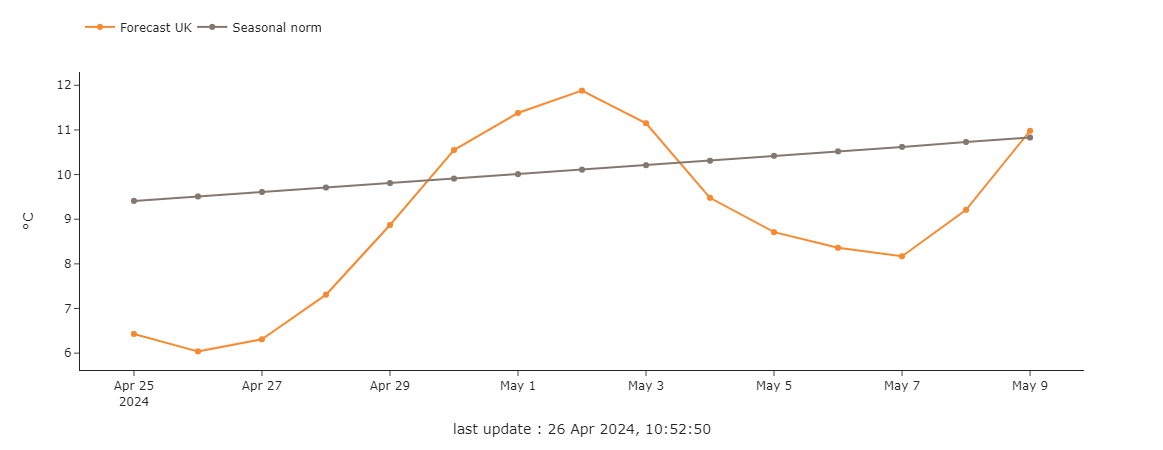
- Looking to the continent, near-term delivery prices have been supported over the last couple of weeks by temperatures below seasonal norms (increasing heating demand).
- It’s interesting to note the geographical differences across Europe – cold in the SW, warm in the NW (centred around the Netherlands).
- Prices therefore are easing in the warmer regions.
- Windy conditions are expected for the coming week and should be much higher than the seasonal average.
- Solar generation is also likely to be high over Central Western Europe – though confidence in a sustained period of renewables outputs is weak – so the benign fundamentals could dissipate rapidly!
- On the Carbon markets, EUAs (European Allowances or EU-ETS) continued to rebound yesterday after retesting the €65/tn level on Wednesday (supported by the 20-day moving average).
- Back in the UK, Dec-24 contracts for UK ETS are circa. £37/tn.
- Temperatures are expected back above seasonal norms come 30th April (see chart).
- Our electricity generation mix is a little bullish in nature today with renewables contributing 20%, thermal at 36% (gas and coal) and low carbon at 28% (nuclear and imports).
- Monthly Day-Ahead averages are on target this month to achieve £50/mwh (or 5p/kwh).