



Fri, 22nd Mar ’24
GAS
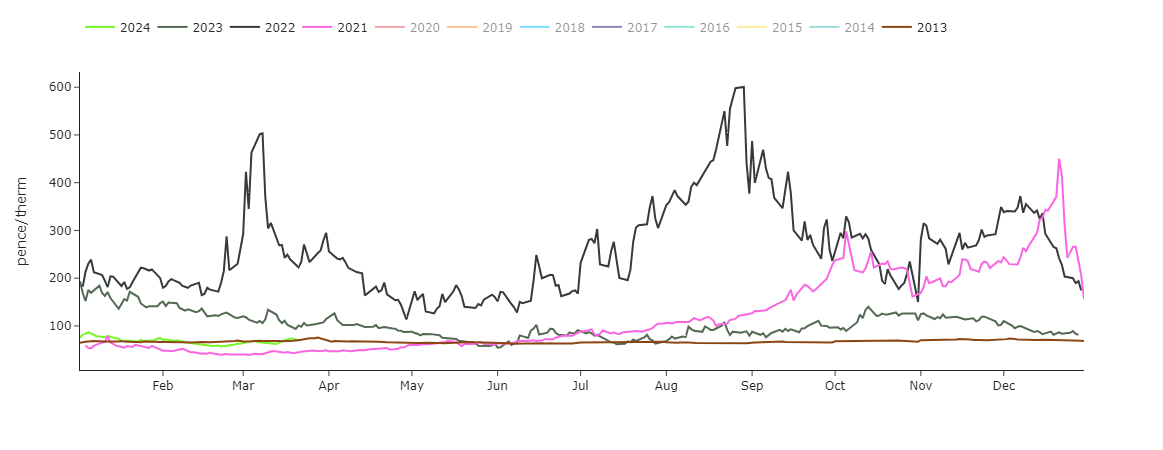
- Month-Ahead prices are now commensurate with those printed in 2013 (though still above early ’21, but way below ’22) – see chart.
- We had another bearish day yesterday, and a sideways day today.
- Temperatures are mild and windy.
- Low exports out of the UK to the continent reflect weak LNG send-out.
- 9 days of Winter-23 remain, and nothing in the fundamentals makes us think that further downside is not going to happen with the onset of summer conditioning – lower demand, high storage, solid Norwegian flows.
- Geopolitically speaking, a ceasefire would likely calm the Red Sea disquiet (and so alleviate the tension around LNG re-routing etc)
- Monthly Day-Ahead averages are on target this month to achieve 68p/therm (or 2.3p/kwh).
ELECTRICITY & CARBON
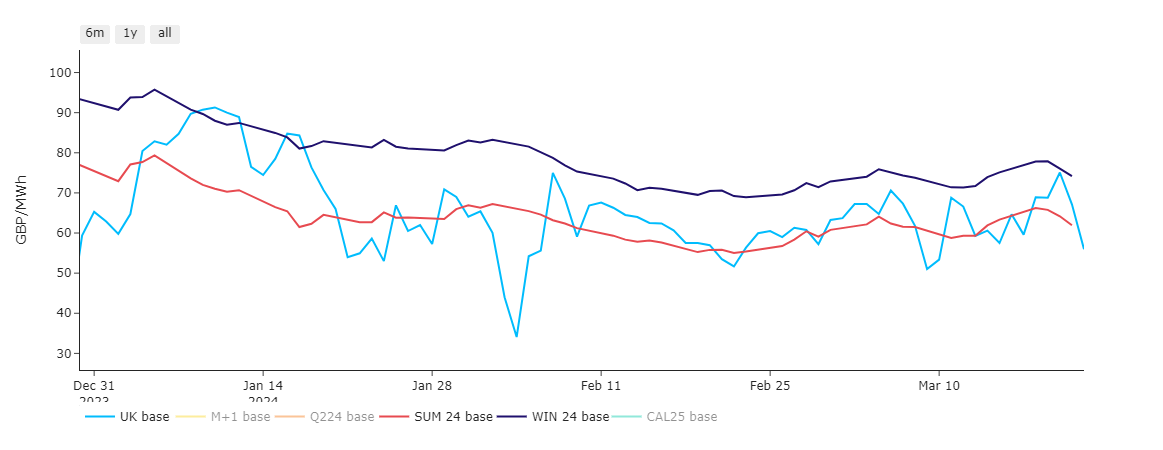
- Day-Ahead continues to use Winter-24 prices as resistance (see chart).
- Looking to the continent, European near-term delivery prices continued to fall as expected yesterday, weighed by soaring wind outputs and falling demand.
- The weekend may see prices plummet due to surging wind production, though the market could find support early next when wind drops off and temperatures fall.
- Though these weather conditions are not expected to last, so it’s all about treading water in a tight price range right now.
- Down the curve, contracts are being dragged down by declining gas and emissions prices (as gas supply reduction worries slowly fade and participants remember the still very comfortable fundamental outlook).
- On the carbon markets, yesterday saw another calm and slightly bearish session, the benchmark contract dropping below the 60 €/t mark in the first hours of trading then slowly decreasing throughout the day.
- Today, it’s been a pretty directionless session with prices having found equilibrium.
- At the time of writing, Dec-24 contracts for UKAs are sitting at £38/tn.
- The UK’s electricity generation mix is bearish in nature today with renewables contributing 44%, thermal at 18% (gas and coal) and low carbon at 26% (nuclear and imports).
- Monthly Day-Ahead averages are on target this month to achieve £65/mwh (or 6.5p/kwh).