



Fri, 21st Nov ’25
GAS
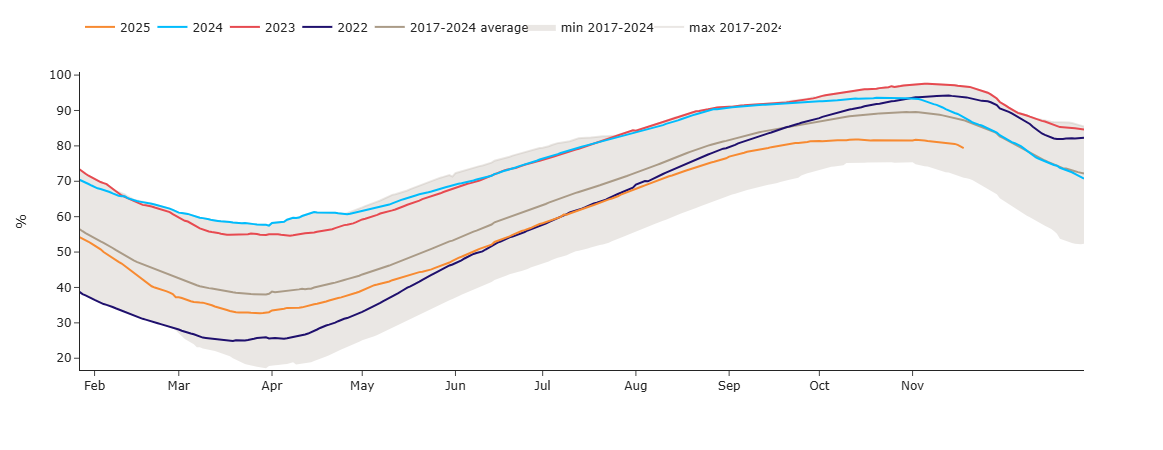
- Low temperatures and patchy wind outputs have inevitably meant high gas-for-power generation this week.
- As such, European storage is threatening to “roll over” into wintry net withdrawal – please see chart below.
- For the time being, inventories remain steady at 80% versus the 7-year average of 87%.
- This morning prompt gas prices opened lower off the back of forecasts predicting temperatures back up above seasonal norms by the end of the month.
- The UK gas system is “long” at the time of writing (supply outstripping demand forecast).
- Down the curve into ’26/’27/’28, gas prices are marginally softer amid news of a potential “peace deal” between Ukraine and Russia.
- Of course, a lasting peace across Eastern Europe would very likely lead to improved gas supplies due to sanctions against Russia being lifted (both pipeline and LNG).
- Market bulls are already staring down the barrel amid the prospect of an LNG glut come ’27 onwards.
- If Russian gas were thrown into the mix, commodity prices would very likely return to pre-pandemic levels.
- Monthly Day-Ahead averages for November so far are at 76p/therm (or 2.6p/kwh exc. non-gas).
- The cosmos in my garden looks to be on its last legs (indicating the heating season can’t be far off)!
ELECTRICITY & CARBON
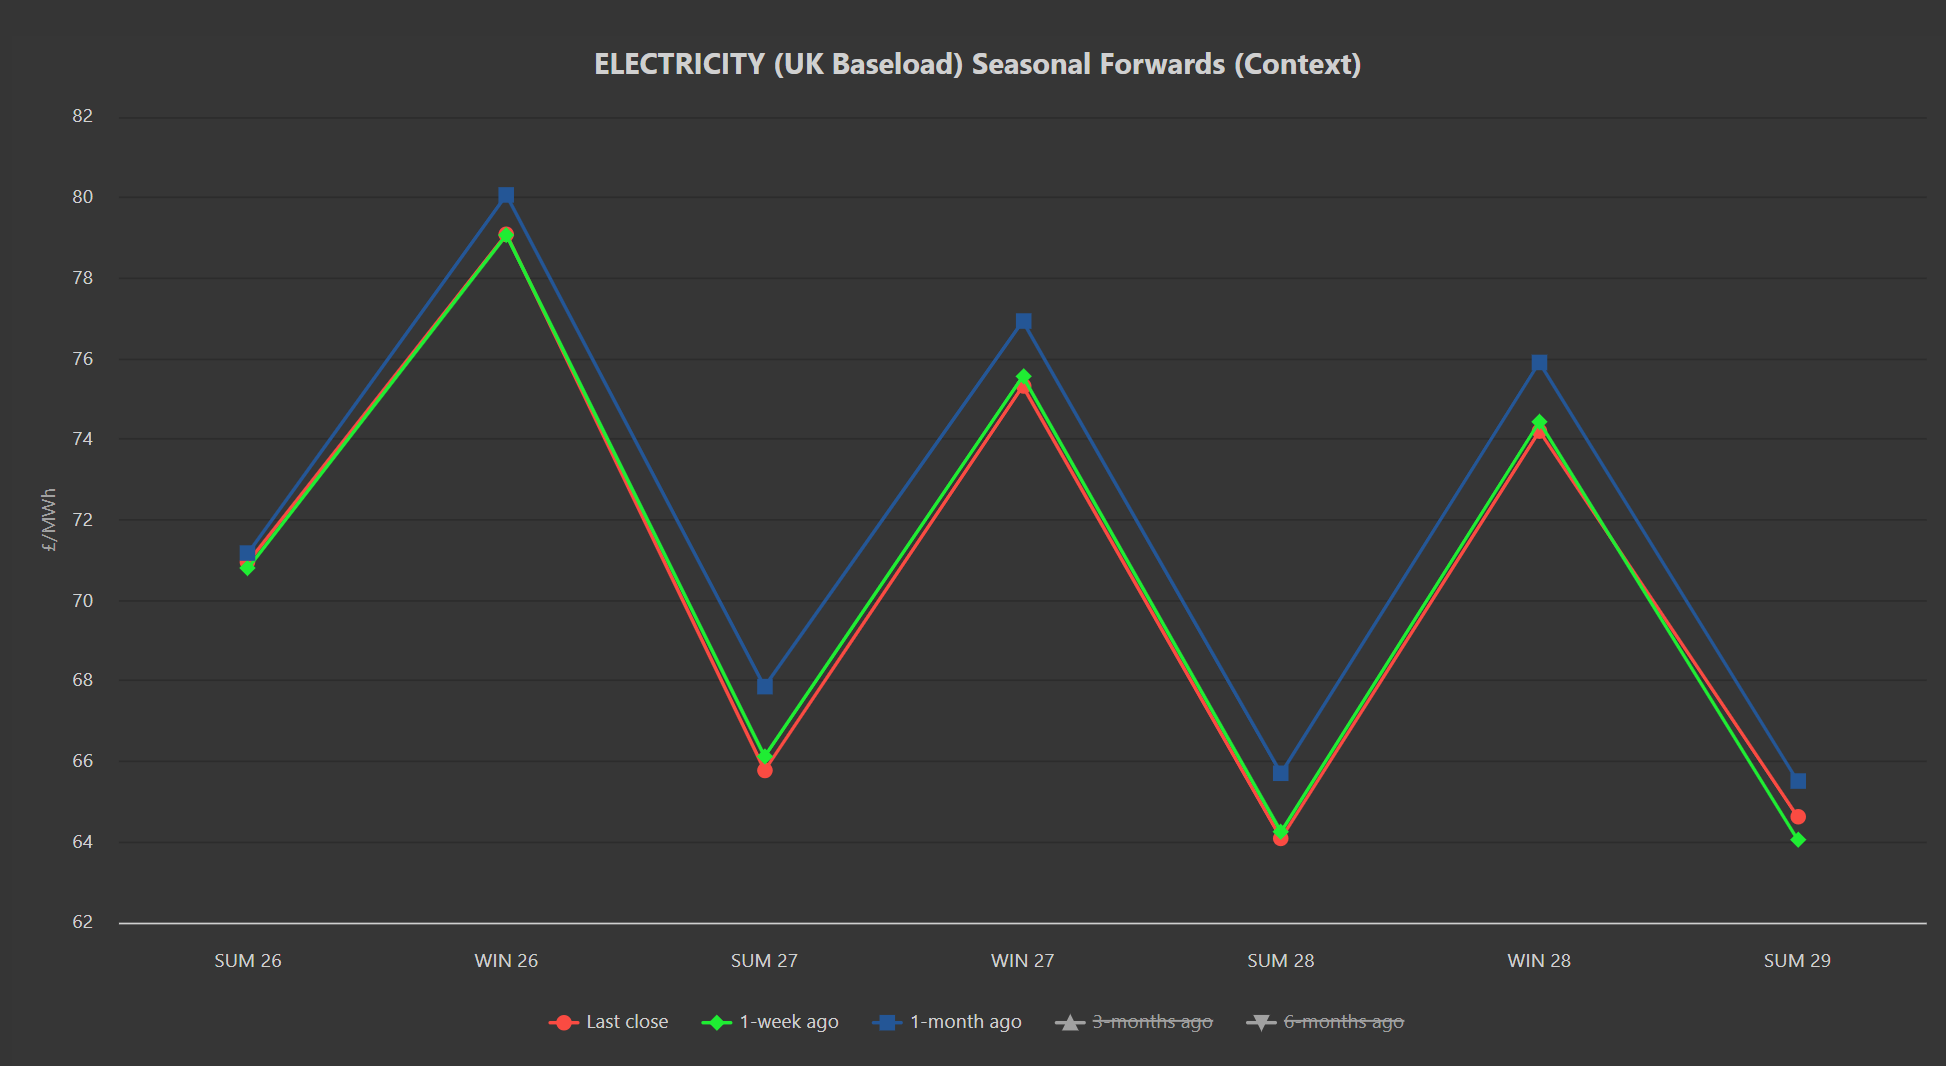
- Electricity Seasonal Forwards remain down on the week, and the month (please see chart below).
- On the Carbon side of things, UKAs continue to trade below the increasingly important resistance level of £58.50/tn, but have failed to fall back (yet) to the increasingly important support level of £55.50/tn.
- Instead, traders are carving out consolidation patterns between these two levels pending bullish/bearish stimulus.
- Today’s UK electricity generation mix is bullish in nature given patchy wind outputs – specifically, renewables are contributing 26%, thermal at 45% (gas and coal) and low carbon at 14% (nuclear and imports).
- Monthly Day-Ahead averages for November so far are at £76/mwh (or 7.6p/kwh exc. non-energy).