



Fri, 20th Mar ’26
GAS
- It’s now been confirmed that Iran’s retaliatory strike on Qatar has severely disabled a major gas facility, likely meaning a global supply crunch that could be with us for several years.
- Concern across the markets this morning has noticably shifted from near-term worries (Summer-26) to mid/long-term impacts (Winter-26 and beyond).
- It’s increasingly difficult not to think that the escalating impacts of war on Iran is playing into Trump’s hands – the US as a net-exporter of oil/gas stands to be the main beneficiary if the Persian Gulf production is hamstrung.
- The wars in Ukraine and now Iran, have shifted the weighting of the global LNG market – the U.S. was the highest LNG exporter in 2025, and Trump has made no secret of his willingness to expand production and exports going forward.
- The US accounts for around 60% of Europe’s LNG imports, while Qatari LNG exports historically supply Asian countries.
- Qatar Energy have announced that 17% of its LNG capacity has been wiped out for 3 to 5 years following Israel’s allegedly unsanctioned attacks – this equates to a 4% global LNG supply shortfall this year.
- This coupled with the Strait of Hormuz remaining shut, and the impending maintenance season of the Norwegian pipeline/fields, leaves Europe/the UK with a serious problem – not just in the short-term, but for the foreseeable future.
- Inevitably, competition for cargoes in the coming months will be fierce with the heating season coming to an end and all eyes on storage replenishment – Europe will be fighting over US imports with South Korea and China.
- Impotent EU leaders can only voice growing concern over the deteriorating economic outlook with the EU looking down the barrel of a recession, and are calling for a temporary halt to strikes on energy infrastructure.
- According to the ECB, an extended disruption could push euro‑area inflation to 6.3% , with gas prices climbing to their highest levels since the Ukriane invasion.
- Meanwhile, the US has outlined moves to boost oil and LNG exports – and so, perhaps, Trump’s motives for enflaming the Middle East are becoming clearer.
- It’s also worth noting that investment funds have increased their net long positions in TTF (benchmark European gas) over the last couple of weeks by more than 600%, further supporting the upward momentum of forward prices.
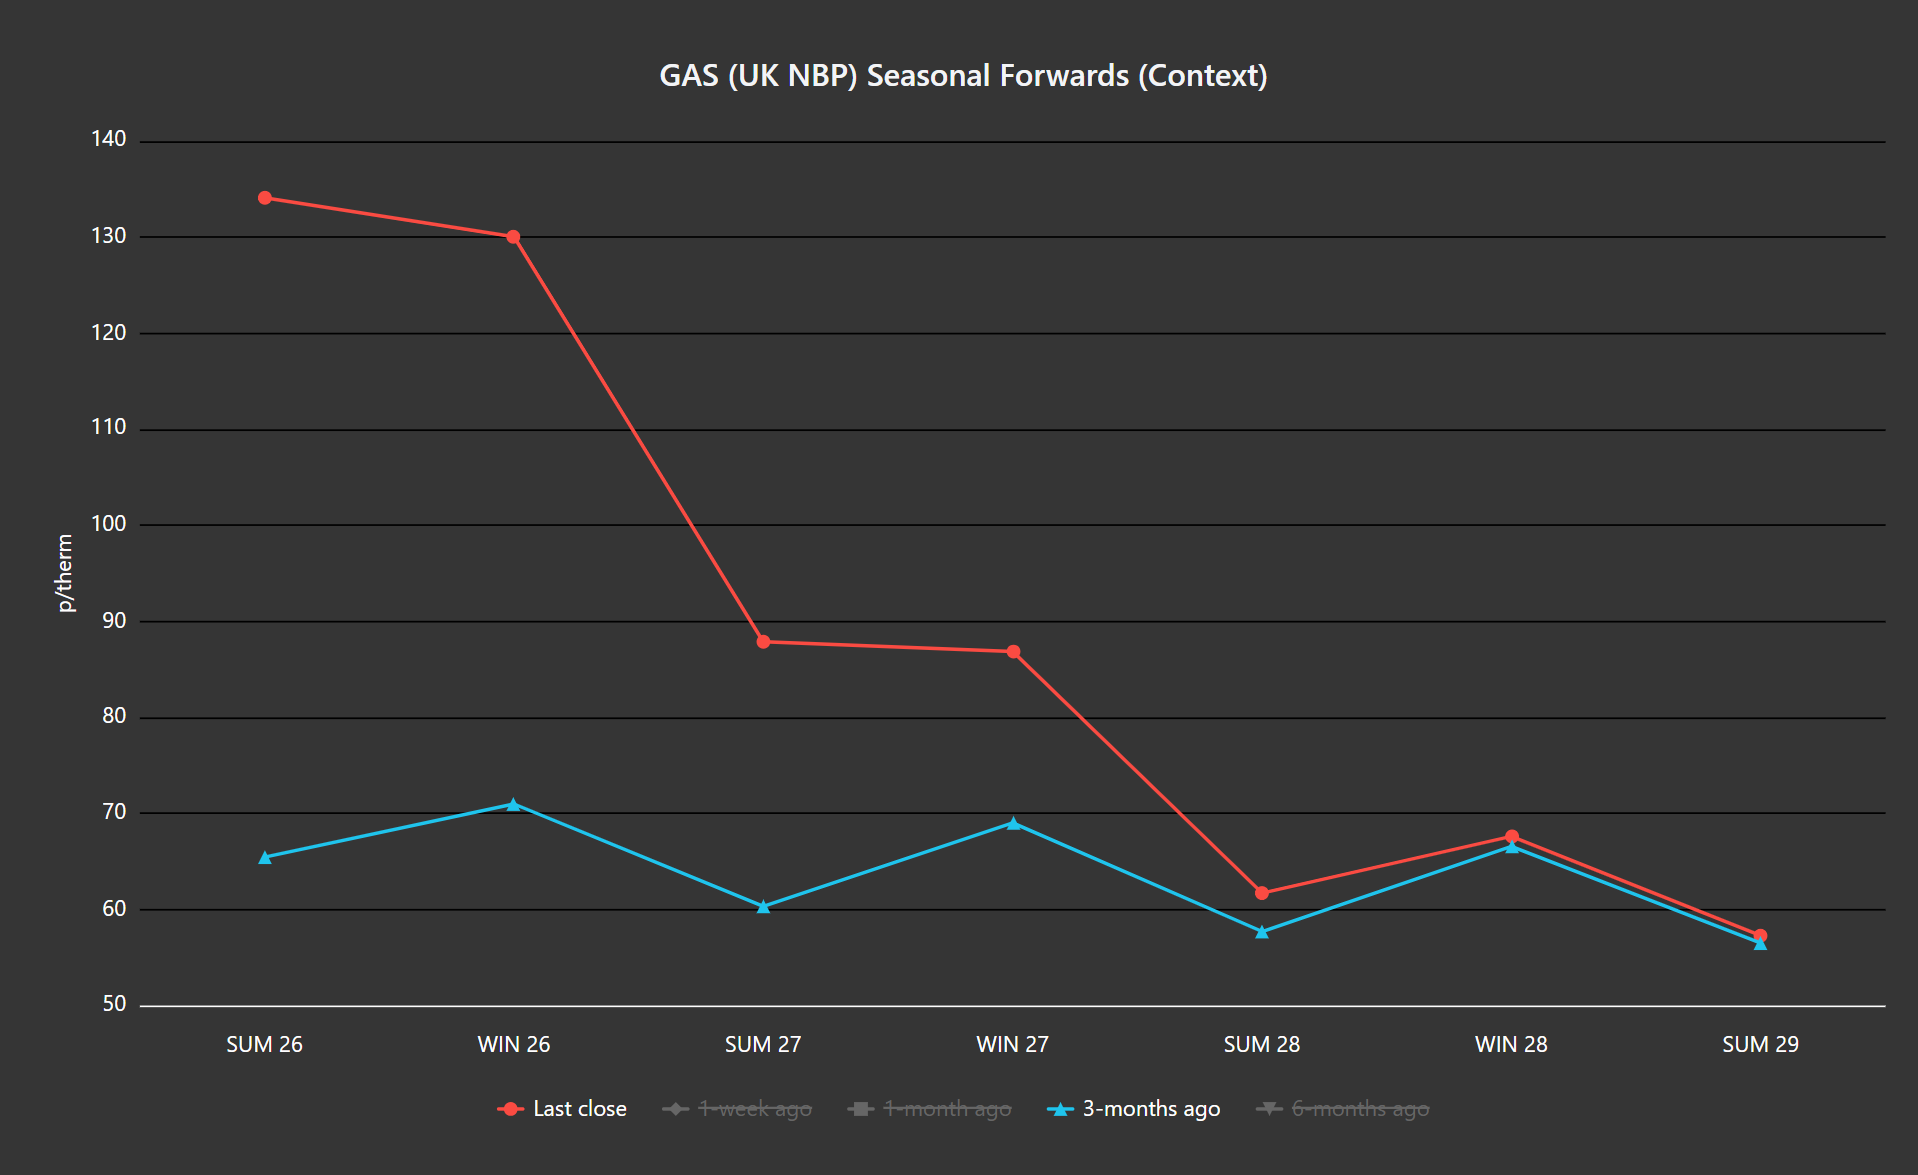
- Not surprisingly, the shape of the whole curve is now shifting – not just the near-term, but the mid-term has also lifted.
- The chart below shows just how badly Trump’s war has impacted prices since mid-Dec ’25 (when it looked as though Europe/the UK would be enjoying a soft-landing beginning Summer-26, with a glut of LNG on the horizon).
- Monthly Day-Ahead averages for the month are slightly up – currently at 127p/therm (or 4.35p/kwh).
ELECTRICITY & CARBON
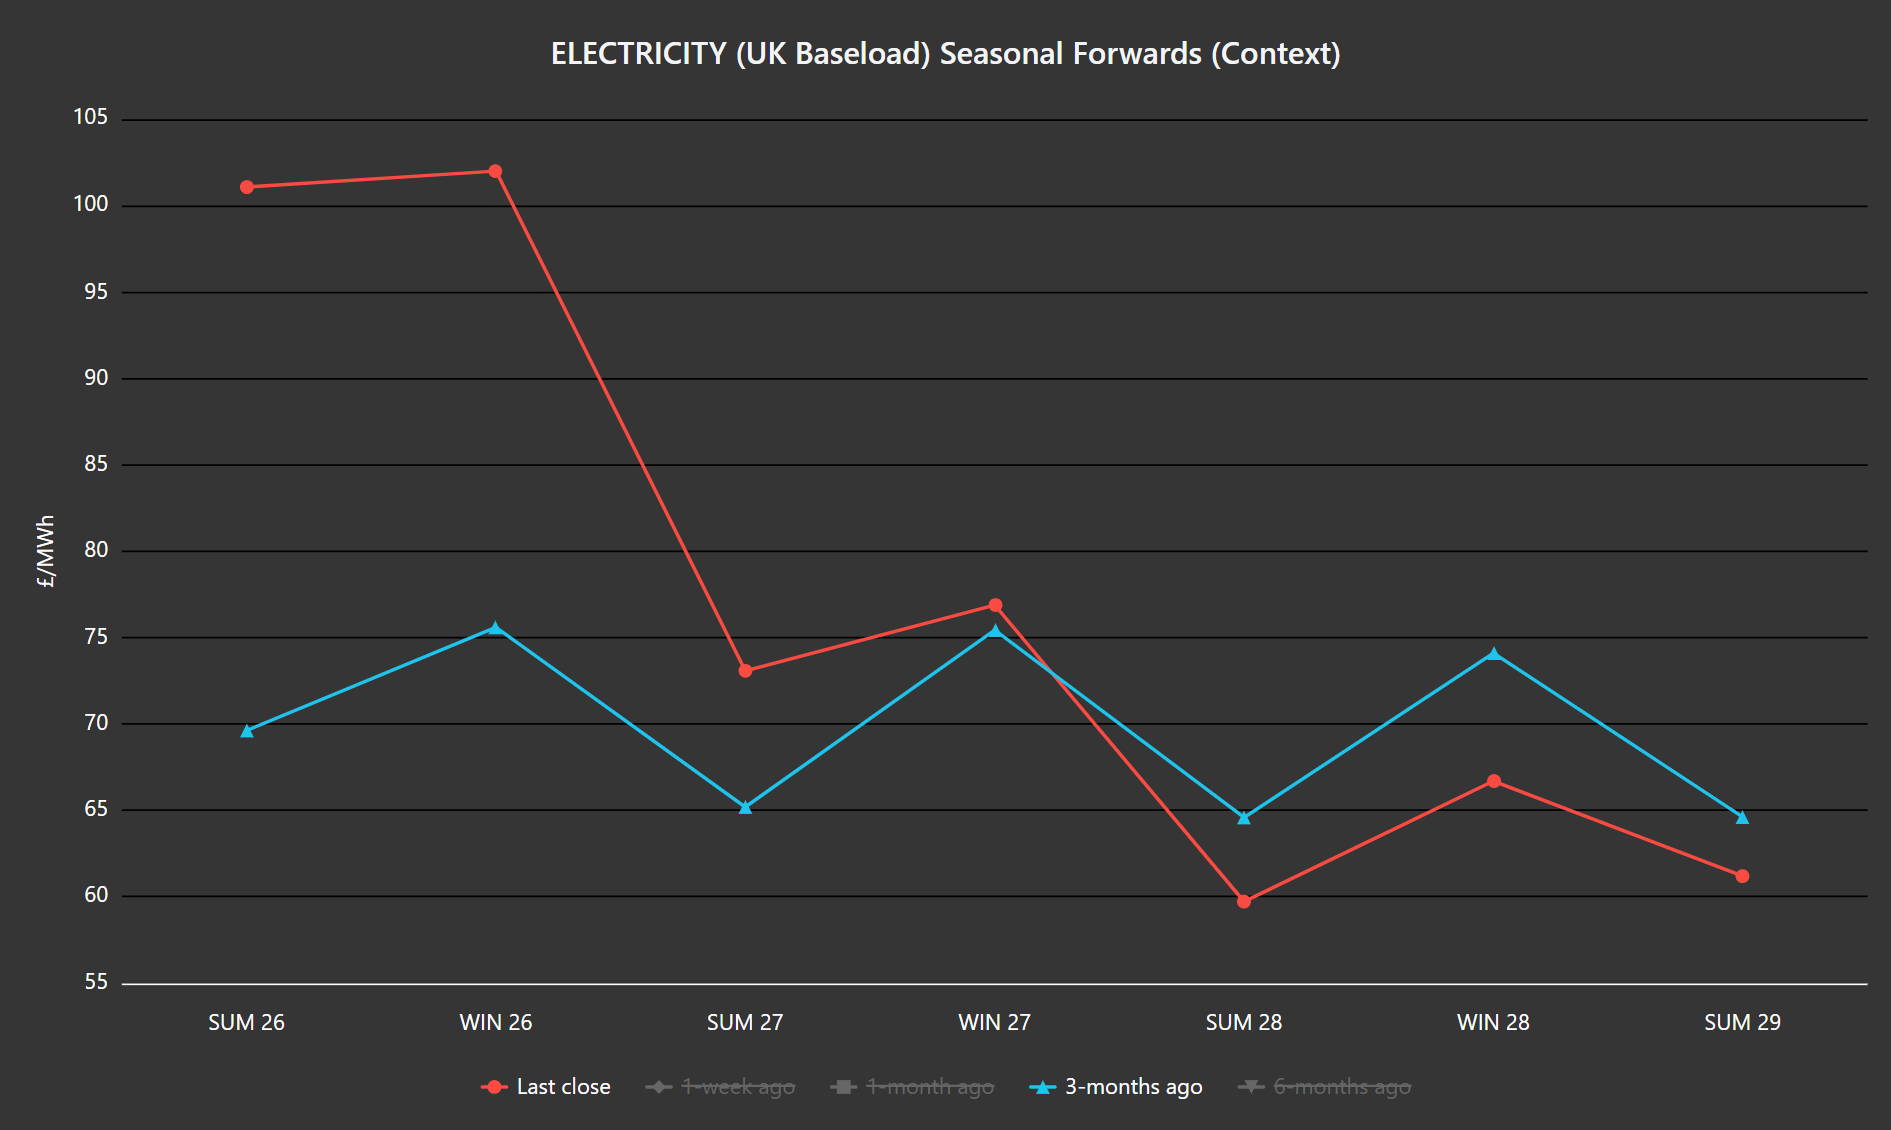
- The chart below again shows Seasonal Forwards at yesterday’s close versus 3-months ago – notably, electricity Forwards have (to date) been less severely impacted than gas prices.
- On the Carbon side of things, Dec-26 UKA delivery remains uncoupled from gas volatility with prices touching levels that are 41% below those printed in mid-Jan amid fears that Trump’s war on Iran is slowing global economies (and, in so doing, Industrial outputs).
- At the time of writing, UKA mid-price Dec ’26 delivery is at £36.52/tn (and the spot is at early-35s).
- Monthly Day-Ahead averages for the month so far are mirroring near-term gas prices – currently at £105/mwh (or 10.5 p/kwh).