



Fri, 13th Feb ’26
GAS
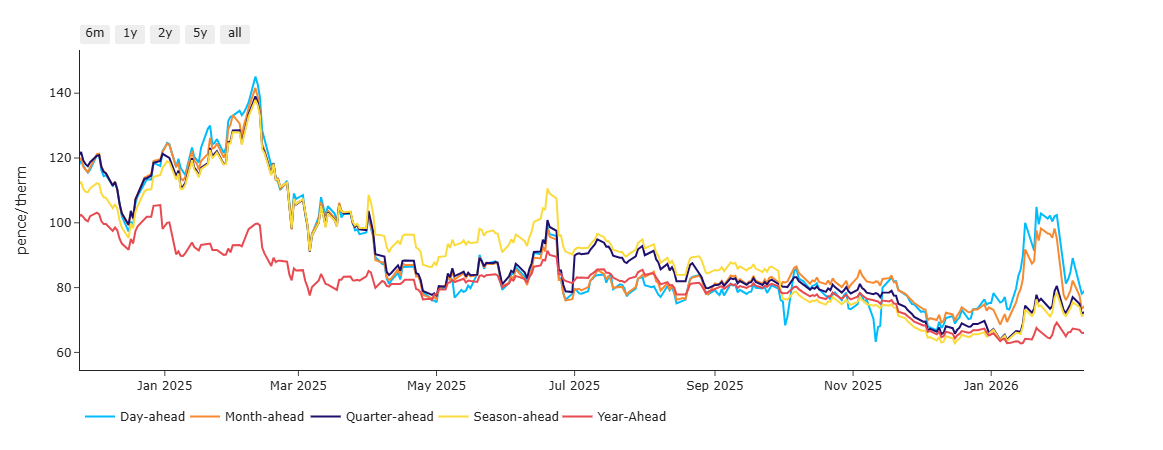
- Near-term delivery remains toward the bottom of a 12-month range (please see chart below).
- In fact, European/UK prices are on-target for their steepest weekly fall since Jun-25 thanks to solid supply offsetting wintry conditions.
- This week has seen bullish days, then bearish corrections, and now sideways price action – reflecting the balancing effect of neutral underlying fundamentals.
- Bears will have been pleased to hear this week that Norway looks set to un-mothball several North Sea fields so as to increase production beginning 2028 (they were closed down in 1998 due to pressure depletion across the chalk reservoirs).
- Bulls are keen to reiterate that European storage fullness is now looking very depleted – 35% versus the 5-year average of 61%.
- Refilling will not begin until Apr-26, so it looks likely we’ll end Winter-25 at levels potentially below the 7-year range (near 20%) – thereafter, those market particpants with a vested interest in seeing prices rise will no doubt spread fear that Summer-26 will need to see higher prices so as to ensure we can refill in time for Winter-26! And so it goes on…
- The truth will be somewhere in the middle – yes, summer refilling will require very solid supply dynamics, but we have those – and given Trump’s latest gambit at reversing emissions restrictions, it would seem very unlikely that the US is going to curtail its LNG exports to European shores any time soon.
- On the strategy side, FLEX clients are still taking small positions further down the curve where there’s great value to be picked up.
- Monthly Day-Ahead averages for the month have fallen slightly to 86p/therm (or 2.9p/kwh).
ELECTRICITY & CARBON
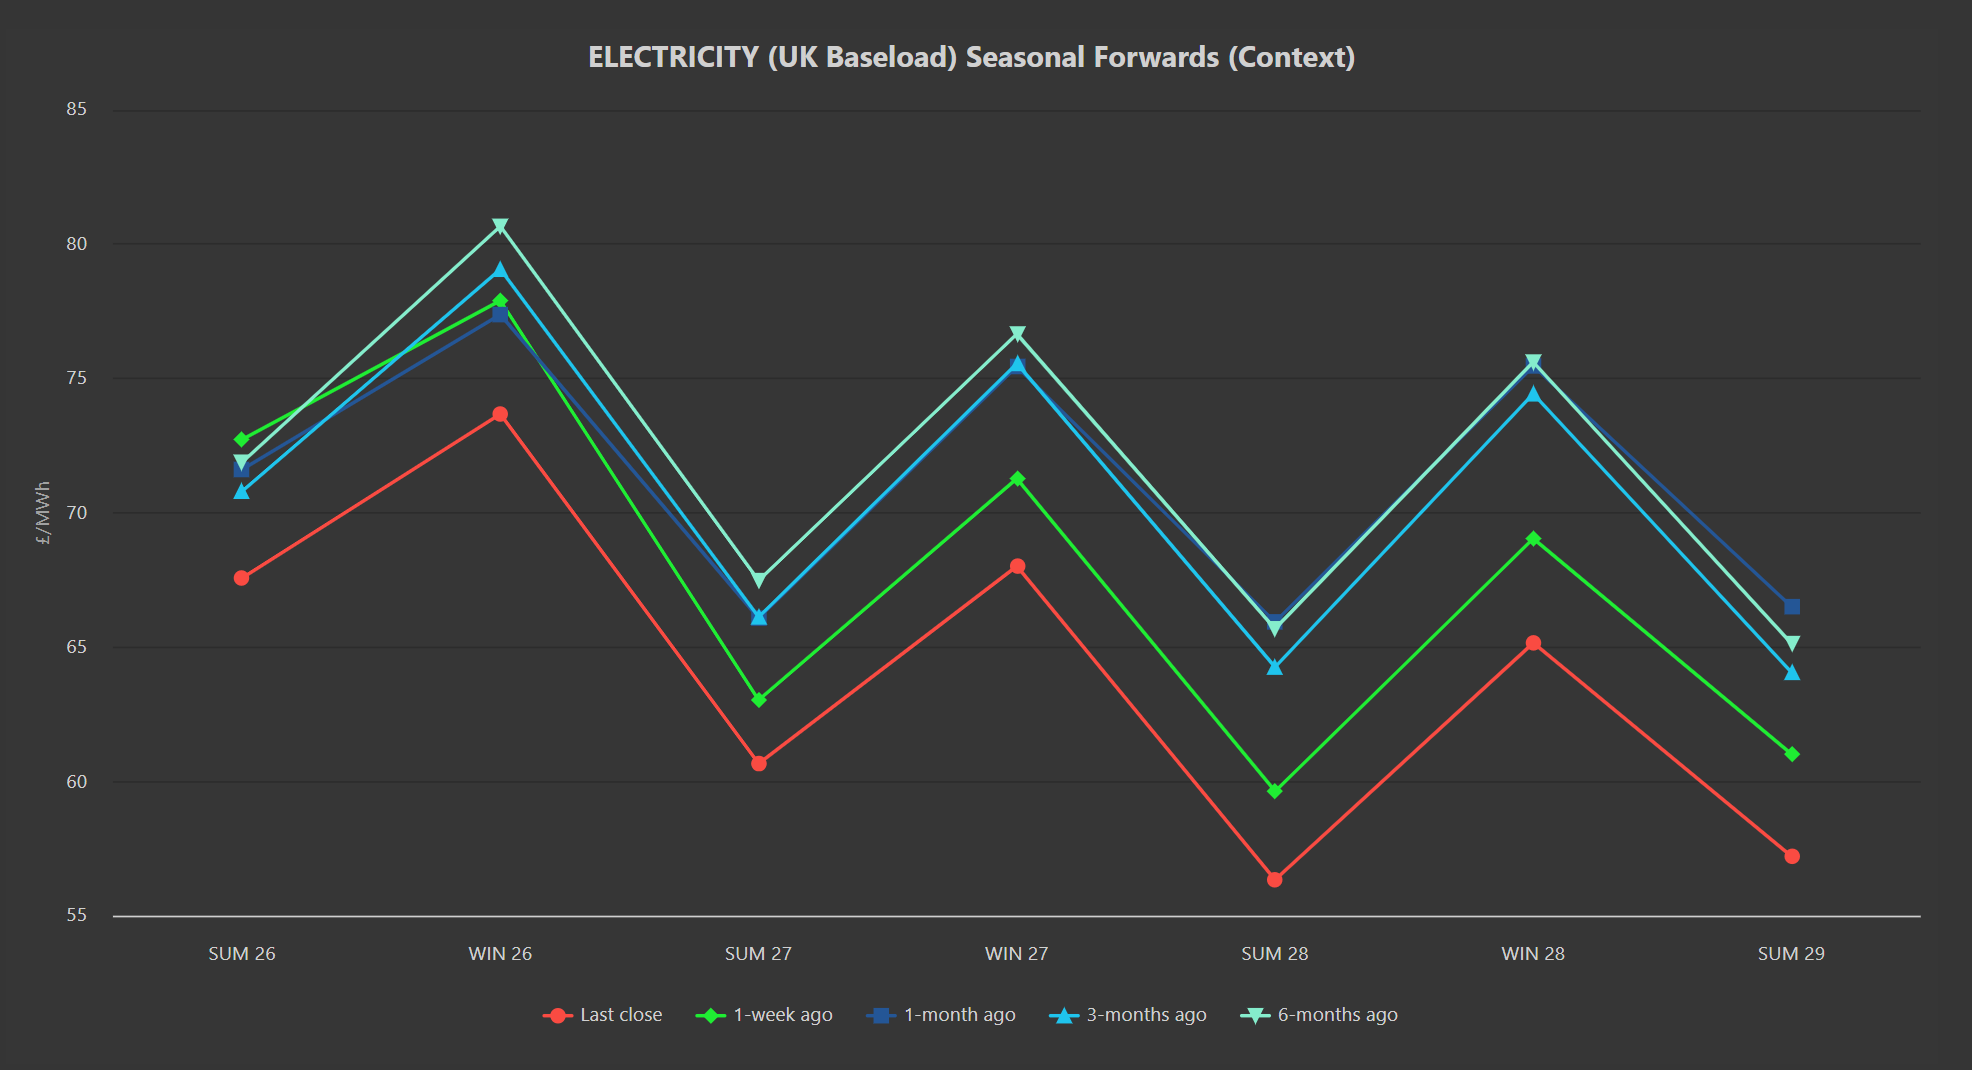
- Seasonal Forwards all the way down the curve are lower on the week/month/3-months/6-months (see chart below).
- On the Carbon side of things, both EUAs and UKAs have been in free fall amid revelations that make Starmer’s premiership look increasingly shaky.
- Front December delivery over the last 12-months has seen a march northwards beginning Jan-25 when Starmer first announced his plans to re-link EUETS and UKETS.
- Since his potentially imminent demise has come to the fore in the last week or so, UKAs have become disproportionately bearish with re-linkage looking less likely.
- At the time of writing, Dec-26 UKA delivery has fallen to £45.42/tn (down 40% in a just a fortnight!)
- Compliance buyers can only look on and scratch their heads as to how they can budget accurately for a tax which rises and falls with such erratic volatility.
- Today’s UK electricity generation mix is bullish in nature – specifically, renewables are contributing 29%, thermal at 46% (gas and coal) and low carbon at 16% (nuclear and imports).
- Monthly Day-Ahead averages for the month so far remain wintry at £95/mwh (or 9.5p/kwh exc. non-energy).